

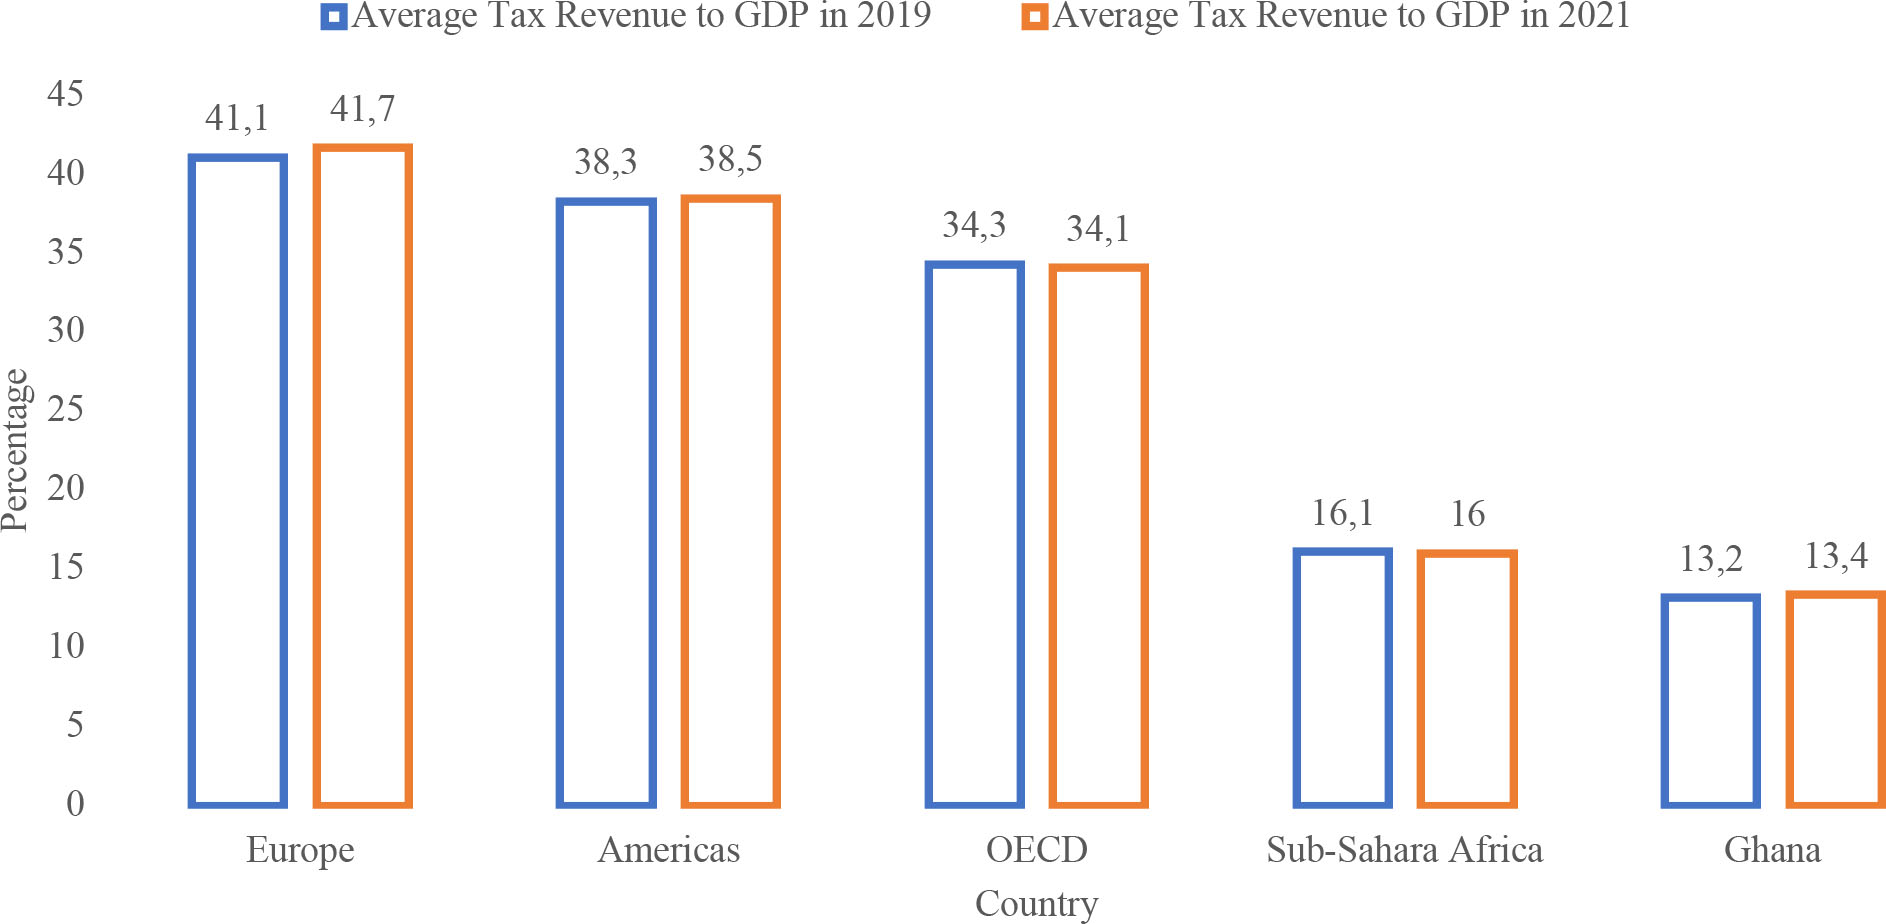
Figure 1.
Tax revenue-to-GDP
(Source: OECD Revenue Statistics, 2022)
Table 1.
Analysis of Liquidity Funds/Total Deposits
(Source: Ghxana Banking Survey Report, 2023)
| Banks | 2022 | R | 2021 | R | 2020 | R | 2019 | R | 2018 | R | 2017 | R |
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| FBN | 1.31 | 1 | 1.00 | 9 | 0.98 | 7 | 1.32 | 3 | 1.78 | 2 | 1.10 | 5 |
| BOA | 1.04 | 2 | 1.40 | 1 | 0.95 | 10 | 1.05 | 7 | 0.74 | 14 | 0.79 | 19 |
| ABG | 0.97 | 3 | 1.10 | 5 | 1.02 | 5 | 0.94 | 10 | 0.93 | 9 | 0.87 | 11 |
| FBL | 0.95 | 4 | 1.27 | 2 | 0.98 | 8 | 1.46 | 2 | 1.17 | 5 | 1.03 | 6 |
| FNB | 0.90 | 5 | 1.14 | 4 | 1.16 | 1 | 1.65 | 1 | 2.81 | 1 | 1.89 | 3 |
| SCB | 0.90 | 6 | 0.99 | 10 | 0.95 | 9 | 0.93 | 11 | 0.98 | 8 | 0.86 | 14 |
| UBA | 0.89 | 7 | 0.92 | 11 | 0.93 | 11 | 0.97 | 9 | 1.33 | 4 | 0.87 | 12 |
| PBL | 0.88 | 8 | 0.90 | 13 | 0.79 | 15 | 0.59 | 17 | 0.57 | 19 | 0.70 | 21 |
| ABSA | 0.82 | 9 | 1.16 | 3 | 1.02 | 6 | 1.25 | 5 | 1.13 | 6 | 0.69 | 22 |
| OBL | 0.82 | 10 | 0.92 | 12 | 0.73 | 19 | 0.00 | - | 0.00 | - | 0.88 | 10 |
| ZBL | 0.81 | 11 | 1.07 | 8 | 1.12 | 2 | 1.26 | 4 | 1.34 | 3 | 0.96 | 7 |
| CBG | 0.75 | 12 | 1.09 | 7 | 1.04 | 4 | 1.10 | 6 | 0.00 | - | 0.00 | - |
| GCB | 0.75 | 13 | 0.90 | 14 | 0.87 | 13 | 0.79 | 14 | 0.8 | 12 | 0.85 | 15 |
| GTB | 0.75 | 14 | 0.76 | 16 | 0.90 | 12 | 1.03 | 8 | 1.05 | 7 | 0.96 | 8 |
| SBG | 0.71 | 15 | 0.68 | 20 | 0.74 | 18 | 0.58 | 18 | 0.66 | 17 | 0.83 | 17 |
| CAL | 0.70 | 16 | 1.10 | 6 | 1.07 | 3 | 0.89 | 12 | 0.77 | 13 | 0.79 | 18 |
| RBL | 0.69 | 17 | 0.71 | 19 | 0.70 | 20 | 0.69 | 15 | 0.72 | 15 | 0.66 | 23 |
| UMB | 0.67 | 18 | 0.00 | - | 0.54 | 23 | 0.00 | - | 0.00 | - | 0.86 | 13 |
| SG-GH | 0.66 | 19 | 0.76 | 17 | 0.62 | 21 | 0.45 | 19 | 0.65 | 18 | 0.53 | 26 |
| EBG | 0.64 | 20 | 0.73 | 18 | 0.74 | 17 | 0.59 | 16 | 0.71 | 16 | 0.76 | 20 |
| ADB | 0.63 | 21 | 0.77 | 15 | 0.79 | 14 | 0.83 | 13 | 0.89 | 10 | 0.84 | 16 |
| FABL | 0.58 | 22 | 0.62 | 21 | 0.77 | 16 | 0.00 | 1 | 0.88 | 11 | 0.89 | 9 |
Table 2.
Banks’ Liquid Funds/Total Assets
(Source: Ghana Banking Survey Report, 2023)
| Banks | 2022 | R | 2021 | R | 2020 | R | 2019 | R | 2018 | R | 2017 | R |
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| FBN | 0.76 | 1 | 0.65 | 11 | 0.66 | 8 | 0.74 | 6 | 0.89 | 1 | 0.82 | 3 |
| ABG | 0.73 | 2 | 0.76 | 4 | 0.73 | 3 | 0.65 | 9 | 0.67 | 8 | 0.63 | 9 |
| SCB | 0.72 | 3 | 0.75 | 5 | 0.69 | 4 | 0.69 | 8 | 0.71 | 7 | 0.63 | 10 |
| CBG | 0.71 | 4 | 0.84 | 1 | 0.87 | 1 | 0.91 | 1 | 0.00 | - | 0.00 | - |
| ZBL | 0.70 | 5 | 0.77 | 3 | 0.81 | 2 | 0.85 | 2 | 0.83 | 2 | 0.72 | 8 |
| OBL | 0.69 | 6 | 0.70 | 7 | 0.63 | 11 | 0.00 | - | 0.00 | - | 0.62 | 12 |
| UBA | 0.69 | 7 | 0.71 | 6 | 0.68 | 7 | 0.77 | 4 | 0.79 | 4 | 0.61 | 14 |
| FBL | 0.68 | 8 | 0.78 | 2 | 0.69 | 5 | 0.73 | 7 | 0.75 | 6 | 0.76 | 4 |
| GCB | 0.63 | 9 | 0.68 | 9 | 0.68 | 6 | 0.62 | 10 | 0.63 | 11 | 0.62 | 13 |
| BOA | 0.59 | 10 | 0.65 | 10 | 0.55 | 19 | 0.57 | 13 | 0.47 | 16 | 0.52 | 22 |
| GTB | 0.59 | 11 | 0.56 | 17 | 0.66 | 9 | 0.75 | 5 | 0.76 | 5 | 0.75 | 7 |
| SBG | 0.58 | 12 | 0.55 | 18 | 0.59 | 17 | 0.45 | 17 | 0.48 | 15 | 0.56 | 18 |
| PBL | 0.57 | 13 | 0.59 | 15 | 0.49 | 21 | 0.39 | 18 | 0.42 | 18 | 0.47 | 25 |
| FNB | 0.57 | 14 | 0.61 | 12 | 0.59 | 16 | 0.82 | 3 | 0.81 | 3 | 0.75 | 6 |
| RBL | 0.56 | 15 | 0.54 | 19 | 0.53 | 20 | 0.53 | 14 | 0.55 | 13 | 0.54 | 19 |
| EBG | 0.55 | 16 | 0.60 | 14 | 0.60 | 13 | 0.49 | 15 | 0.53 | 14 | 0.60 | 16 |
| ABSA | 0.54 | 17 | 0.60 | 13 | 0.56 | 18 | 0.59 | 12 | 0.62 | 12 | 0.53 | 20 |
| CAL | 0.51 | 18 | 0.69 | 8 | 0.60 | 14 | 0.49 | 16 | 0.45 | 17 | 0.47 | 24 |
| UMB | 0.50 | 19 | 0.00 | - | 0.38 | 23 | 0.00 | - | 0.00 | - | 0.56 | 17 |
| ADB | 0.50 | 20 | 0.58 | 16 | 0.59 | 15 | 0.62 | 11 | 0.64 | 10 | 0.60 | 15 |
| FABL | 0.49 | 21 | 0.52 | 20 | 0.62 | 12 | 0.00 | - | 0.65 | 9 | 0.76 | 5 |
| SG-GH | 0.43 | 22 | 0.47 | 21 | 0.42 | 22 | 0.32 | 19 | 0.41 | 19 | 0.38 | 26 |
Table 3.
Banks’ Liquid Funds to Total Interest Bearing Liabilities
(Source: Ghana Banking Survey Report, 2023)
| Banks | 2022 | R | 2021 | R | 2020 | R | 2019 | R | 2018 | R | 2017 | R |
|---|---|---|---|---|---|---|---|---|---|---|---|---|
| FBN | 1.29 | 1 | 0.99 | 2 | 0.96 | 3 | 1.28 | 2 | 1.78 | 2 | 1.01 | 4 |
| UBA | 0.89 | 2 | 0.92 | 6 | 0.93 | 4 | 0.97 | 6 | 1.00 | 5 | 0.77 | 12 |
| ABG | 0.87 | 3 | 0.95 | 4 | 0.92 | 5 | 0.79 | 10 | 0.83 | 9 | 0.76 | 13 |
| SCB | 0.87 | 4 | 0.93 | 5 | 0.91 | 6 | 0.86 | 7 | 0.92 | 6 | 0.84 | 10 |
| OBL | 0.80 | 5 | 0.87 | 8 | 0.69 | 18 | 0.00 | - | 0.00 | - | 0.75 | 14 |
| ZBL | 0.80 | 6 | 1.03 | 1 | 1.05 | 1 | 1.08 | 3 | 1.04 | 4 | 0.88 | 9 |
| BOA | 0.75 | 7 | 0.87 | 9 | 0.82 | 8 | 0.81 | 8 | 0.59 | 16 | 0.63 | 22 |
| GTB | 0.74 | 8 | 0.75 | 14 | 0.88 | 7 | 1.03 | 5 | 1.04 | 3 | 0.94 | 6 |
| FBL | 0.73 | 9 | 0.88 | 7 | 0.80 | 11 | 0.81 | 9 | 0.85 | 8 | 0.88 | 8 |
| CBG | 0.71 | 10 | 0.98 | 3 | 1.01 | 2 | 1.08 | 4 | 0.00 | - | 0.00 | - |
| GCB | 0.71 | 11 | 0.84 | 10 | 0.81 | 9 | 0.75 | 12 | 0.77 | 11 | 0.75 | 15 |
| SBG | 0.71 | 12 | 0.68 | 19 | 0.73 | 14 | 0.57 | 17 | 0.65 | 15 | 0.80 | 11 |
| FNB | 0.68 | 13 | 0.81 | 11 | 0.81 | 10 | 1.56 | 1 | 2.81 | 1 | 1.89 | 2 |
| ABSA | 0.68 | 14 | 0.76 | 13 | 0.73 | 15 | 0.73 | 13 | 0.76 | 12 | 0.69 | 18 |
| RBL | 0.68 | 15 | 0.68 | 18 | 0.67 | 19 | 0.65 | 14 | 0.67 | 14 | 0.64 | 21 |
| EBG | 0.64 | 16 | 0.73 | 15 | 0.74 | 13 | 0.58 | 15 | 0.70 | 13 | 0.74 | 16 |
| PBL | 0.63 | 17 | 0.73 | 16 | 0.60 | 20 | 0.49 | 18 | 0.52 | 19 | 0.55 | 25 |
| FABL | 0.58 | 18 | 0.62 | 21 | 0.77 | 12 | 0.00 | - | 0.88 | 7 | 0.89 | 7 |
| SG-GH | 0.57 | 19 | 0.65 | 20 | 0.56 | 22 | 0.43 | 19 | 0.56 | 17 | 0.51 | 26 |
| CAL | 0.56 | 20 | 0.80 | 12 | 0.71 | 16 | 0.57 | 16 | 0.54 | 18 | 0.58 | 24 |
| ADB | 0.56 | 21 | 0.70 | 17 | 0.71 | 17 | 0.76 | 11 | 0.80 | 10 | 0.71 | 17 |
| UMB | 0.56 | 22 | 0.00 | - | 0.47 | 23 | 0.00 | - | 0.00 | - | 0.66 | 19 |
| TCB | 0.00 | - | 0.00 | - | 0.00 | - | 0.00 | - | 0.00 | - | 20.29 | 1 |
| NIB | 0.00 | - | 0.00 | - | 0.57 | 21 | 0.00 | - | 0.00 | - | 0.00 | - |
| BOB | 0.00 | - | 0.00 | - | 0.00 | - | 0.00 | - | 0.00 | - | 1.12 | 3 |
| PRB | 0.00 | - | 0.00 | - | 0.00 | - | 0.00 | - | 0.00 | - | 0.97 | 5 |
| ECB | 0.00 | - | 0.00 | - | 0.00 | - | 0.00 | - | 0.00 | - | 0.65 | 20 |
| BSIC | 0.00 | - | 0.00 | - | 0.00 | - | 0.00 | - | 0.00 | - | 0.60 | 23 |
| TRB | 0.00 | - | 0.00 | - | 0.00 | - | 0.00 | - | 0.00 | - | 0.26 | 27 |
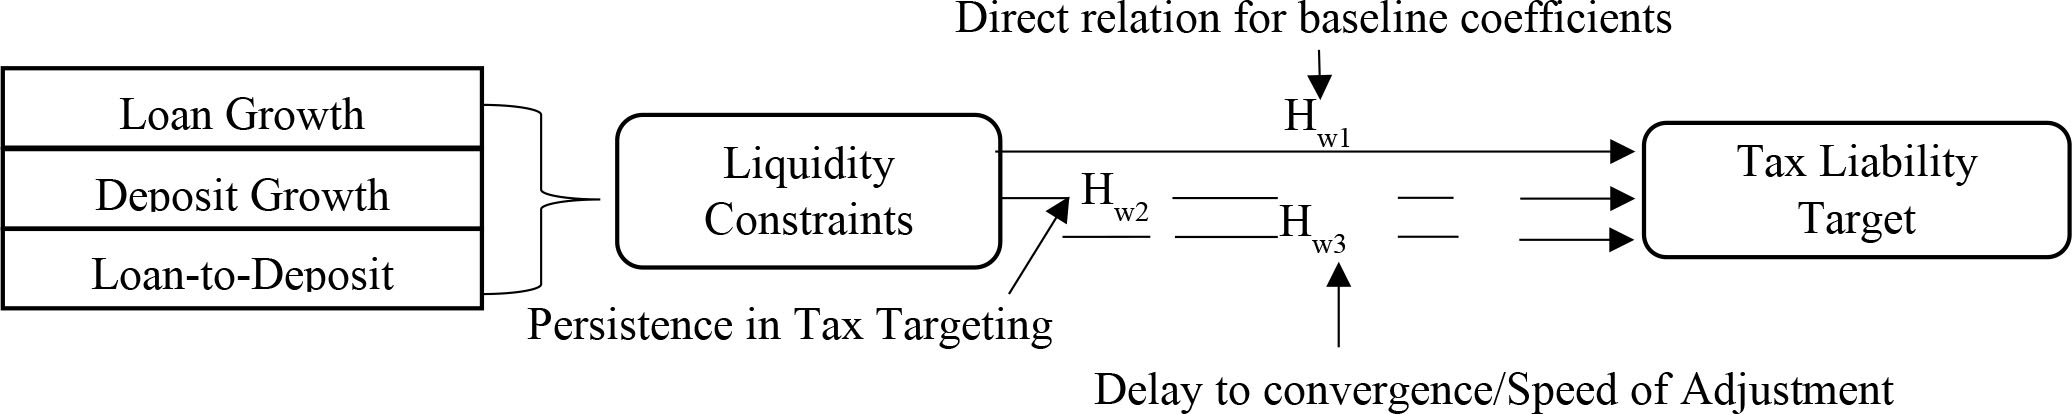
Figure 2.
Framework for liquidity constraint-tax liability targeting, persistence, and delay to convergence
(Source: Authors’ Construct Developed from the Literature)
Table 4.
Variable Description and Measurement
(Source: Authors’ construct developed from varying literature)
| Variables | Description | Measurements |
|---|---|---|
| TLT | Tax liability targeting | |
| CETR | Cash effective tax rate | |
| NLG | Negative loan growth | Loan growth rate multiplied by -1 |
| NDG | Negative deposit growth | Deposit growth rate multiplied by -1 |
| NLD | Negative loan deposit | Loan-to-deposit rate multiplied by -1 |
| BS | Bank size | Log of total assets |
| BA | Bank age | Age of bank |
| BT | Bank tangibility | Carrying balance on PPE |
| BL | Bank leverage | Long-term liability to assets |
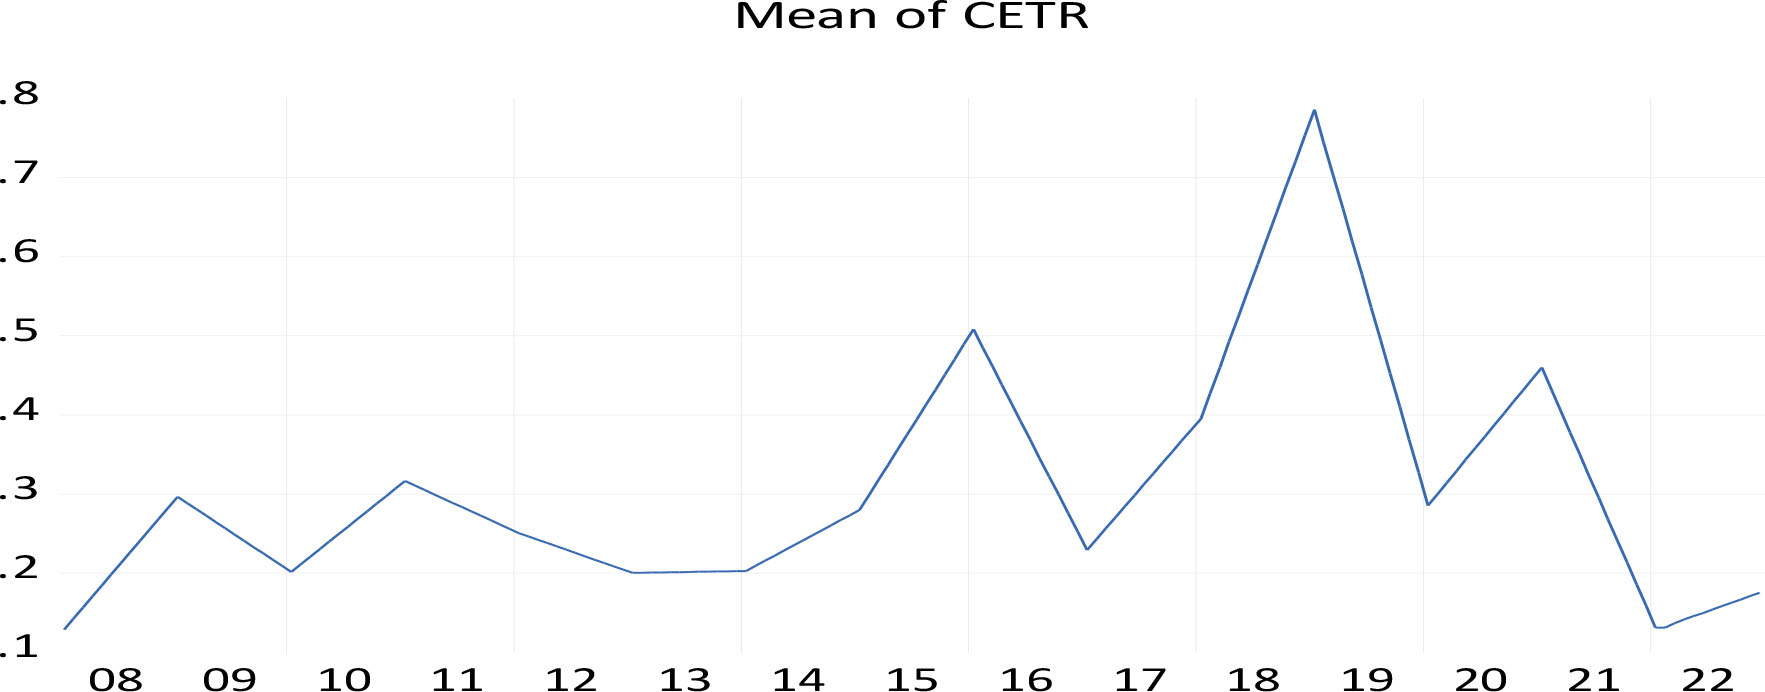
Figure 3.
Time-Varying Mean Trend of Cash Effective Tax Rate (CETR) of Banks in Ghana
(Source: Generated from Eviews version 12.0)
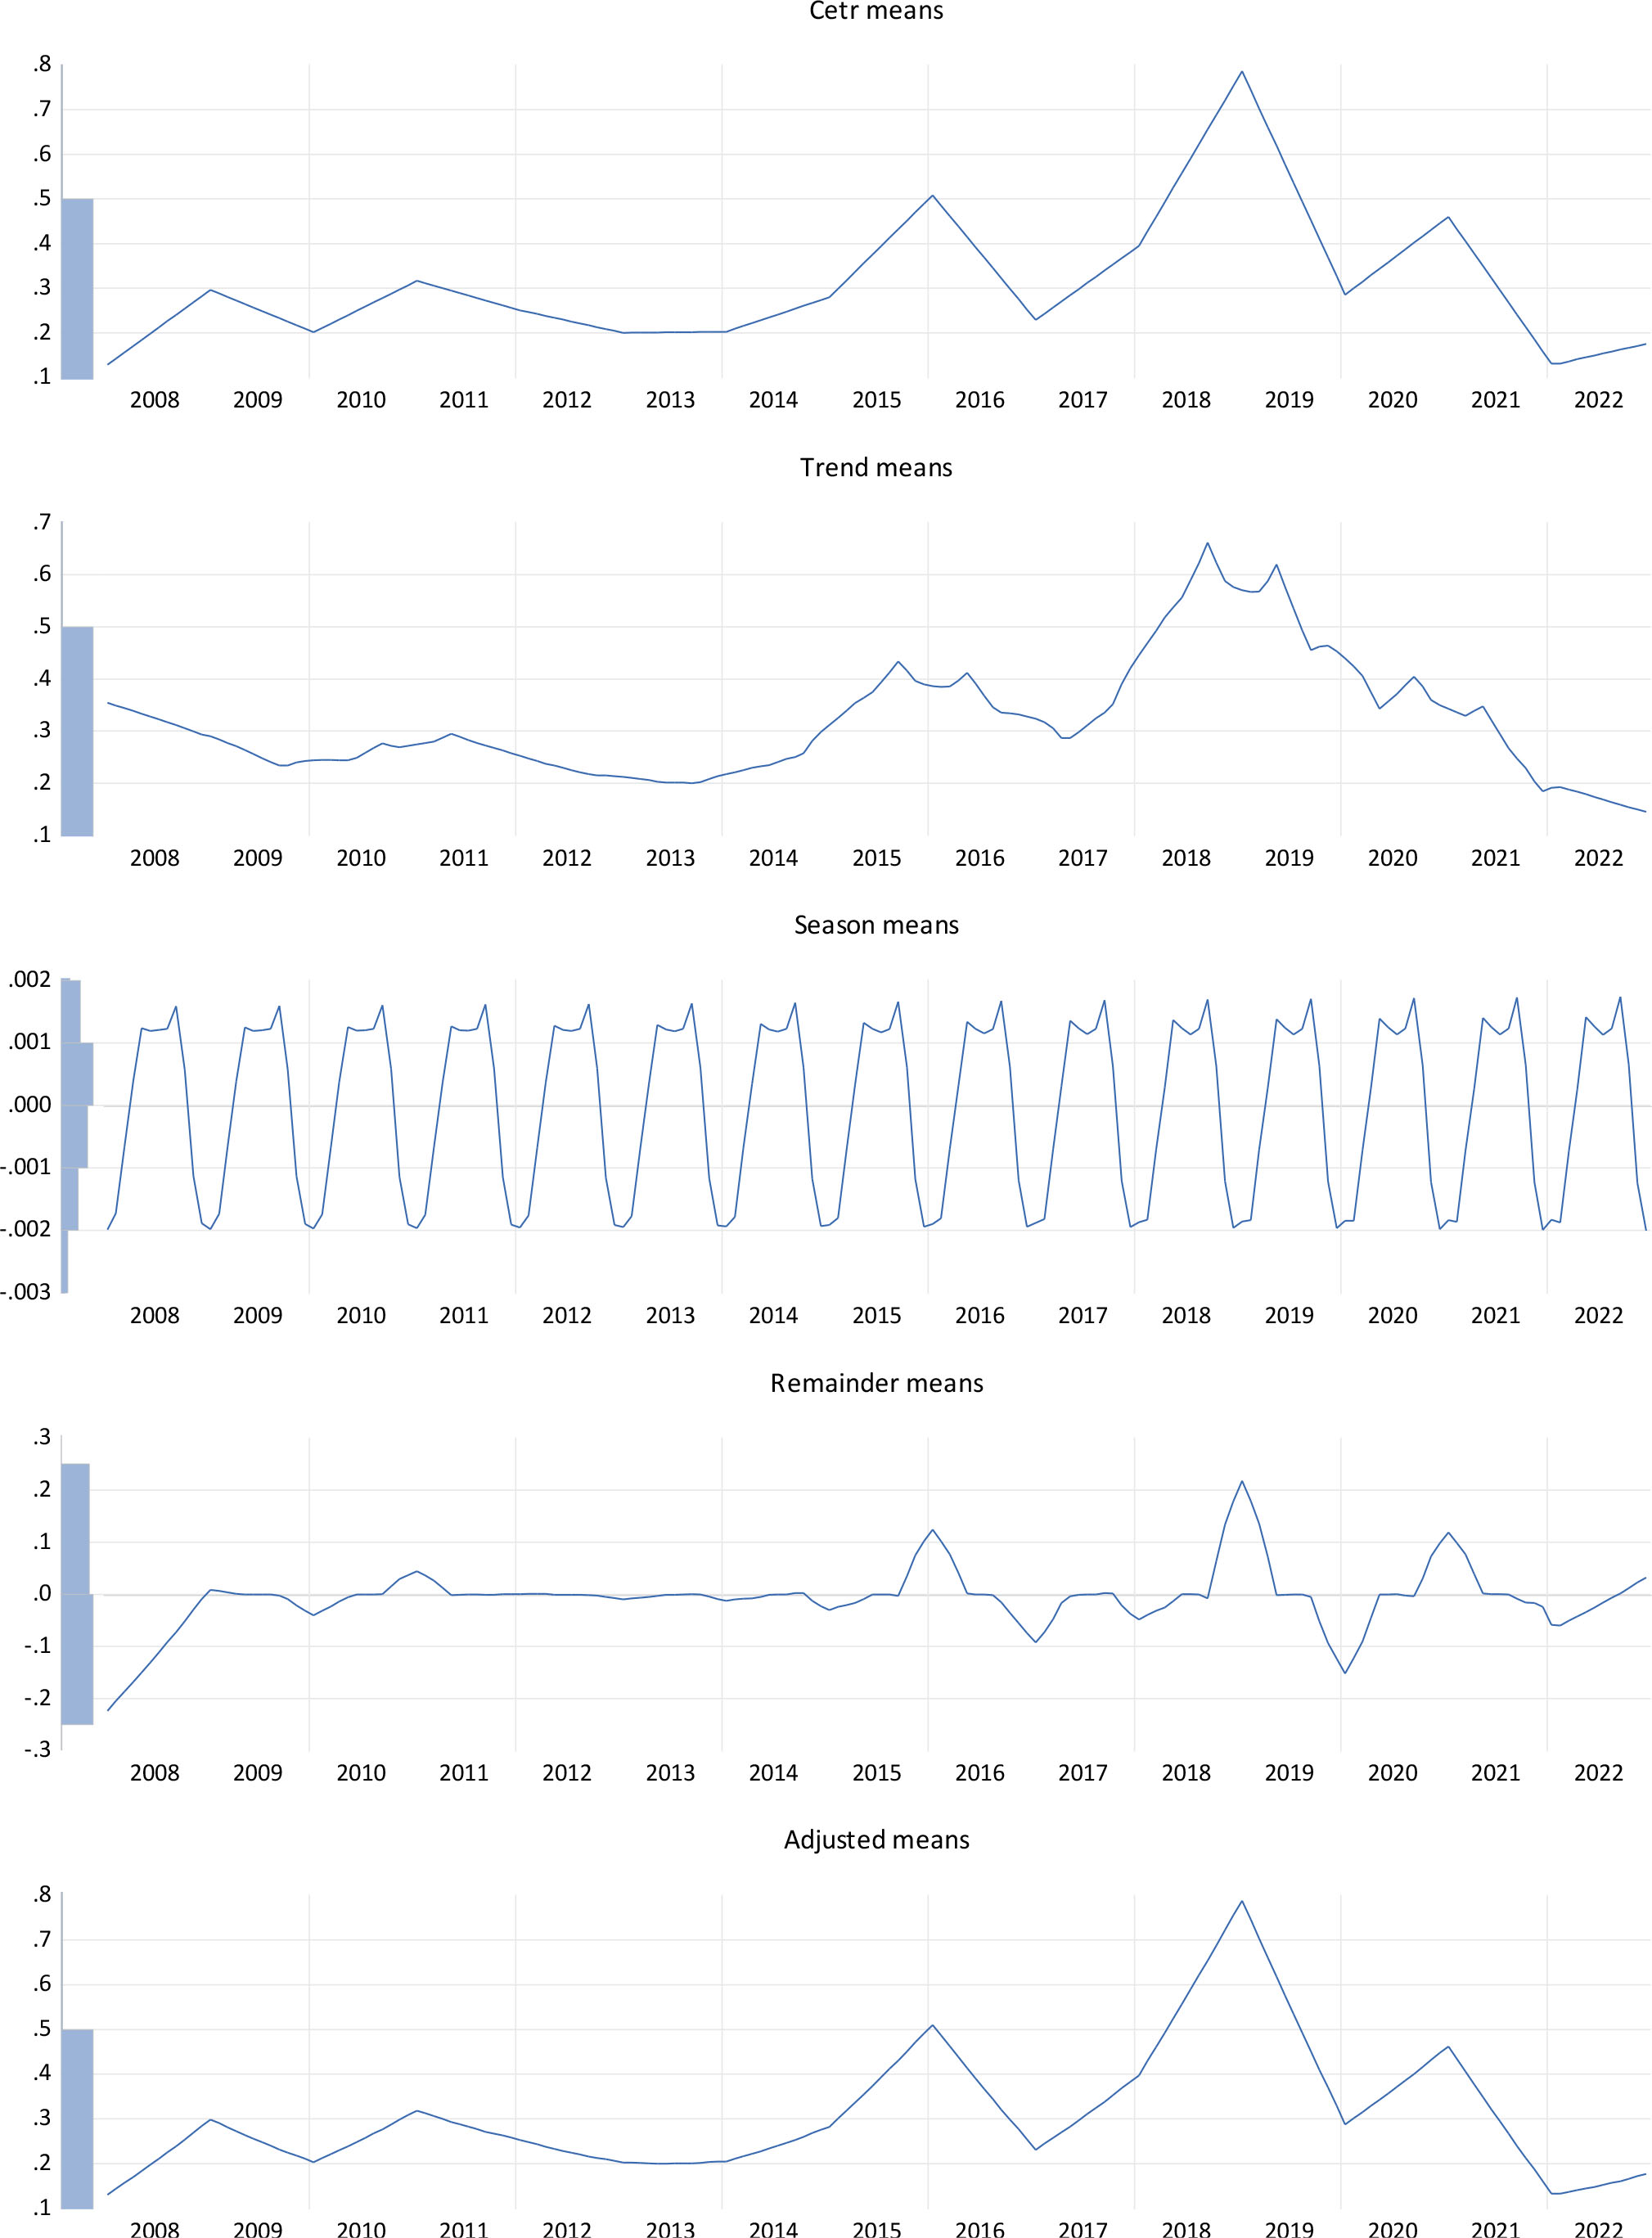
Figure 3.
Disaggregated Observable Patterns in the CETR
(Source: Generated from Eviews version 12.0)
Table 5.
Descriptive Analyses of Tax and Liquidity Constraint Variables
(Source: Generated from Eviews version 12.0)
| CETR | NDG | NLG | NLD | |
|---|---|---|---|---|
| Mean | 0.3129 | -0.4182 | -0.2427 | -1.2871 |
| Median | 0.2686 | -0.2230 | -0.1673 | -0.6010 |
| Maximum | 10.8066 | 0.9891 | 0.8773 | 0.0000 |
| Minimum | -1.9509 | -10.3252 | -3.2301 | -18.0997 |
| Std. Dev. | 0.6416 | 0.8575 | 0.3738 | 2.1419 |
| CoV | 2.0505 | 2.0505 | 1.5402 | 1.6641 |
| Observations | 3600 | 3600 | 3600 | 3600 |
Table 6.
Descriptive Analyses of Control Variables
(Source: Generated from Eviews version 12.0)
| AGE | BL | BS | |
|---|---|---|---|
| Mean | 31.2800 | 0.0899 | 3570000000 |
| Median | 23.2083 | 0.0601 | 2340000000 |
| Maximum | 126.0000 | 0.6289 | 25800000000 |
| Minimum | 1.0000 | 0.0000 | 0.000000 |
| Std. Dev. | 25.5988 | 0.0809 | 3790000000 |
| CoV | 0.8184 | 0.9019 | 1.0616 |
| Observations | 3600 | 3600 | 3600 |
Table 7.
Correlation Matrix of Explanatory Variables
(Source: Generated from Eviews version 12.0)
| CETR | NDG | NLG | NLD | AGE | BL | BS | |
|---|---|---|---|---|---|---|---|
| CETR | 1 | ||||||
| NDG | -0.0251 | 1 | |||||
| NLG | -0.0092 | 0.1114 | 1 | ||||
| NLD | 0.0573 | -0.0059 | 0.0010 | 1 | |||
| AGE | -0.0419 | 0.1322 | 0.2217 | 0.1136 | 1 | ||
| BL | -0.0188 | 0.0505 | 0.1141 | -0.1124 | -0.0036 | 1 | |
| BS | -0.0206 | 0.1087 | 0.0985 | 0.2355 | 0.2332 | 0.0887 | 1 |
Table 8.
Tax Liability Targeting and Liquidity Constraints: DOLS Estimation
(Source: Generated from Eviews version 12.0)
| Variable | Coefficient | Std. Error | t-Statistic | Prob. |
|---|---|---|---|---|
| NDG | -1.6031 | 0.0852 | -18.8198 | 0.0000 |
| NLD | -0.3608 | 0.2022 | -1.7842 | 0.0800 |
| NLG | 0.9731 | 0.1344 | 7.2383 | 0.0000 |
| LAGE | 0.6805 | 0.4541 | 1.4987 | 0.1398 |
| LBS | -0.6407 | 0.1796 | -3.5677 | 0.0008 |
| BL | 0.5050 | 0.7868 | 0.6418 | 0.5237 |
| R-squared | 0.9894 | Mean dependent var | 0.2953 | |
| Adjusted R-squared | 0.9683 | S.D. dependent var | 0.2044 | |
| S.E. of regression | 0.0364 | Sum squared resid | 0.0716 | |
| Long-run variance | 9.35E-05 |
Table 9.
Persistence Analysis: Composite and Cross-Sectional Unit Root Test
(Source: Generated from Eviews version 12.0)
| Method | Statistic | Prob.** |
|---|---|---|
| ADF, Fisher chi-square | 226.312 | 0.0000 |
| ADF, Choi Z-stat | -11.1493 | 0.0000 |
| Intermediate ADF test results: individual cross sections | ||||
|---|---|---|---|---|
| Cross section | Prob. | Lag | Max Lag | Obs |
| ADB | 0.3684 | 2 | 2 | 177 |
| ABSA | 0.0028 | 2 | 2 | 177 |
| ACCESS | 0.0049 | 2 | 2 | 177 |
| BoA | 0.0016 | 2 | 2 | 177 |
| CAL BANK | 0.0016 | 2 | 2 | 177 |
| ECOBANK | 0.0035 | 2 | 2 | 177 |
| FNBBANK | 0.1193 | 2 | 2 | 177 |
| FIRST ATLANTIC | 0.0018 | 2 | 2 | 177 |
| NIB | 0.0643 | 2 | 2 | 177 |
| GT BANK | 0.0002 | 2 | 2 | 177 |
| PRUDENTIAL | 0.0002 | 2 | 2 | 177 |
| REPUBLIC | 0.0005 | 2 | 2 | 177 |
| STANBIC | 0.0005 | 2 | 2 | 177 |
| STANDARD CHARTERED | 0.0036 | 2 | 2 | 177 |
| UMB | 0.0003 | 2 | 2 | 177 |
| ZENITH | 0.0029 | 2 | 2 | 177 |
| FIDELITY | 0.0011 | 2 | 2 | 177 |
| SOCIETE G. | 0.0143 | 2 | 2 | 177 |
| GCB | 0.0002 | 2 | 2 | 177 |
| UBA | 0.9016 | 2 | 2 | 177 |
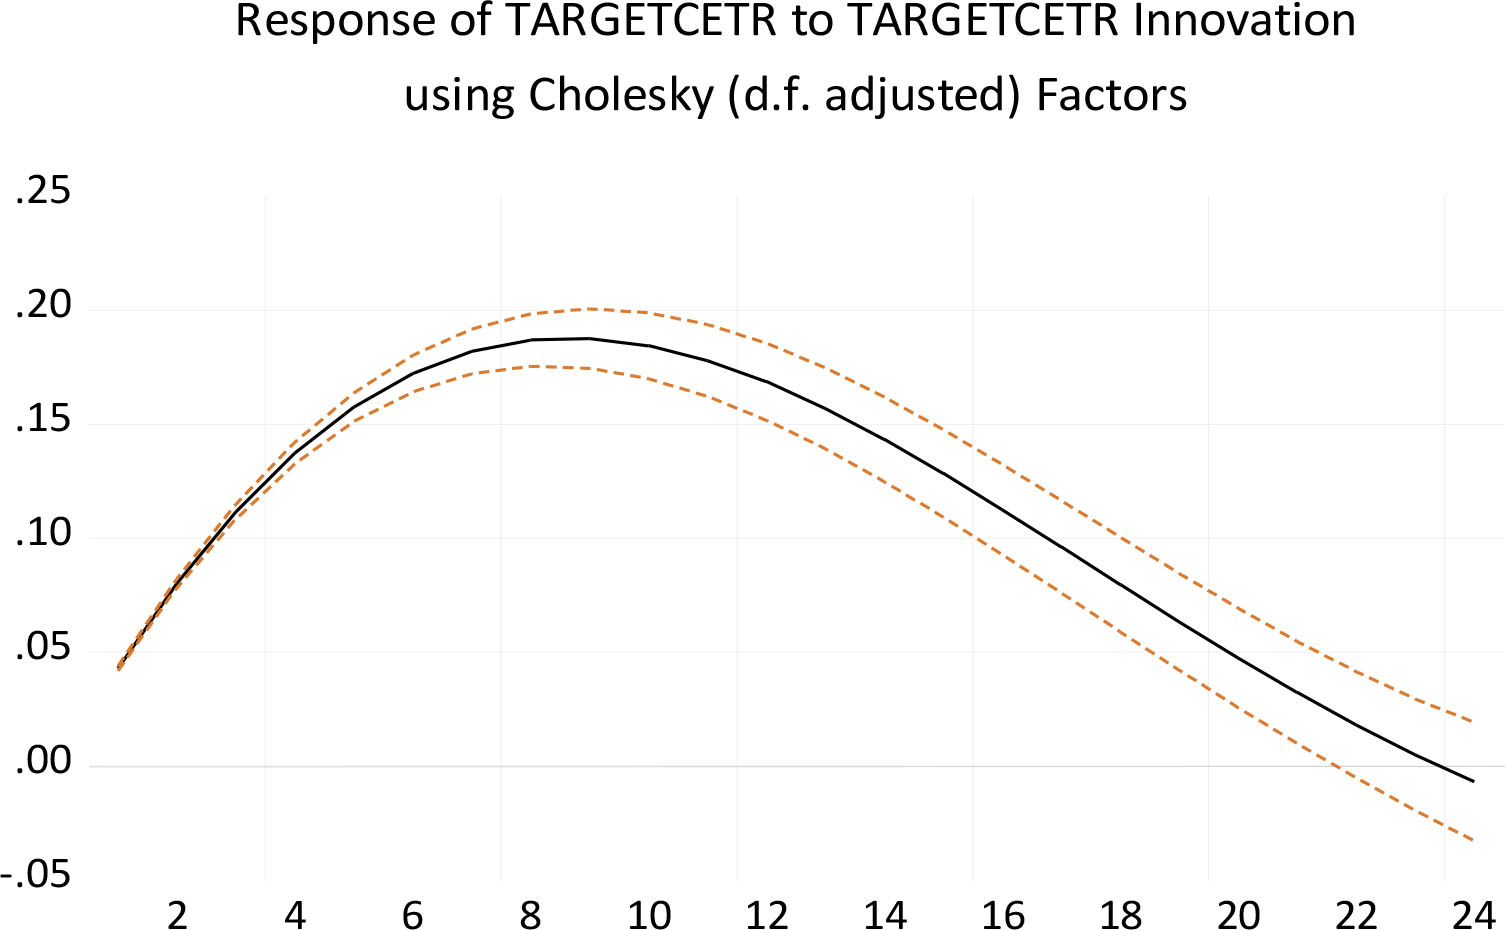
Figure 5.
Impulse Response: Degree of Persistence in Tax Liability Target
(Source: Generated from Eviews version 12.0)
Table 10.
Unit Root of the Residuals
(Source: Generated from Eviews version 12.0)
| Method | Statistic | Prob.** |
|---|---|---|
| Im, Pesaran and Shin W-stat | -7.11459 | 0.0000 |
| ADF, Fisher chi-square | 138.826 | 0.0000 |
| PP, Fisher chi-square | 164.969 | 0.0000 |
Table 11.
Delay Measure, Half-Life, and Speed of Adjustment
(Source: Generated from Eviews version 12.0)
| Variable | Coefficient | Delay | Half-Life | *SOA Rate per Month | Distance to Target in Month |
|---|---|---|---|---|---|
| NDG | -1.6031 | 0.1675 | 0.3880 | 257.73% | 12 days |
| NLD | -0.3608 | 0.4108 | 0.7791 | 128.36% | 23 days |
| NLG | 0.9731 | 0.2743 | 0.5358 | 186.64% | 16 days |