

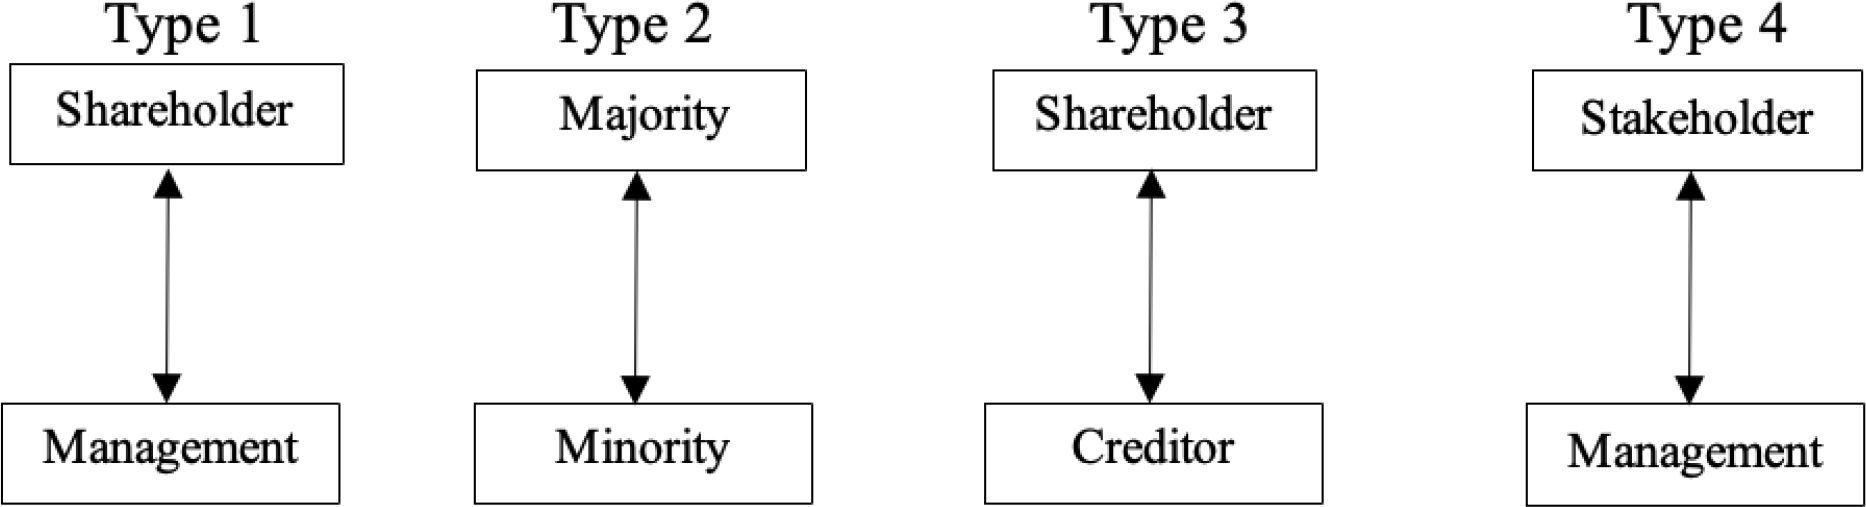
Figure 1.
Type of Agency Problem
(Source: Flayyih and Khiari, 2023, p.201)
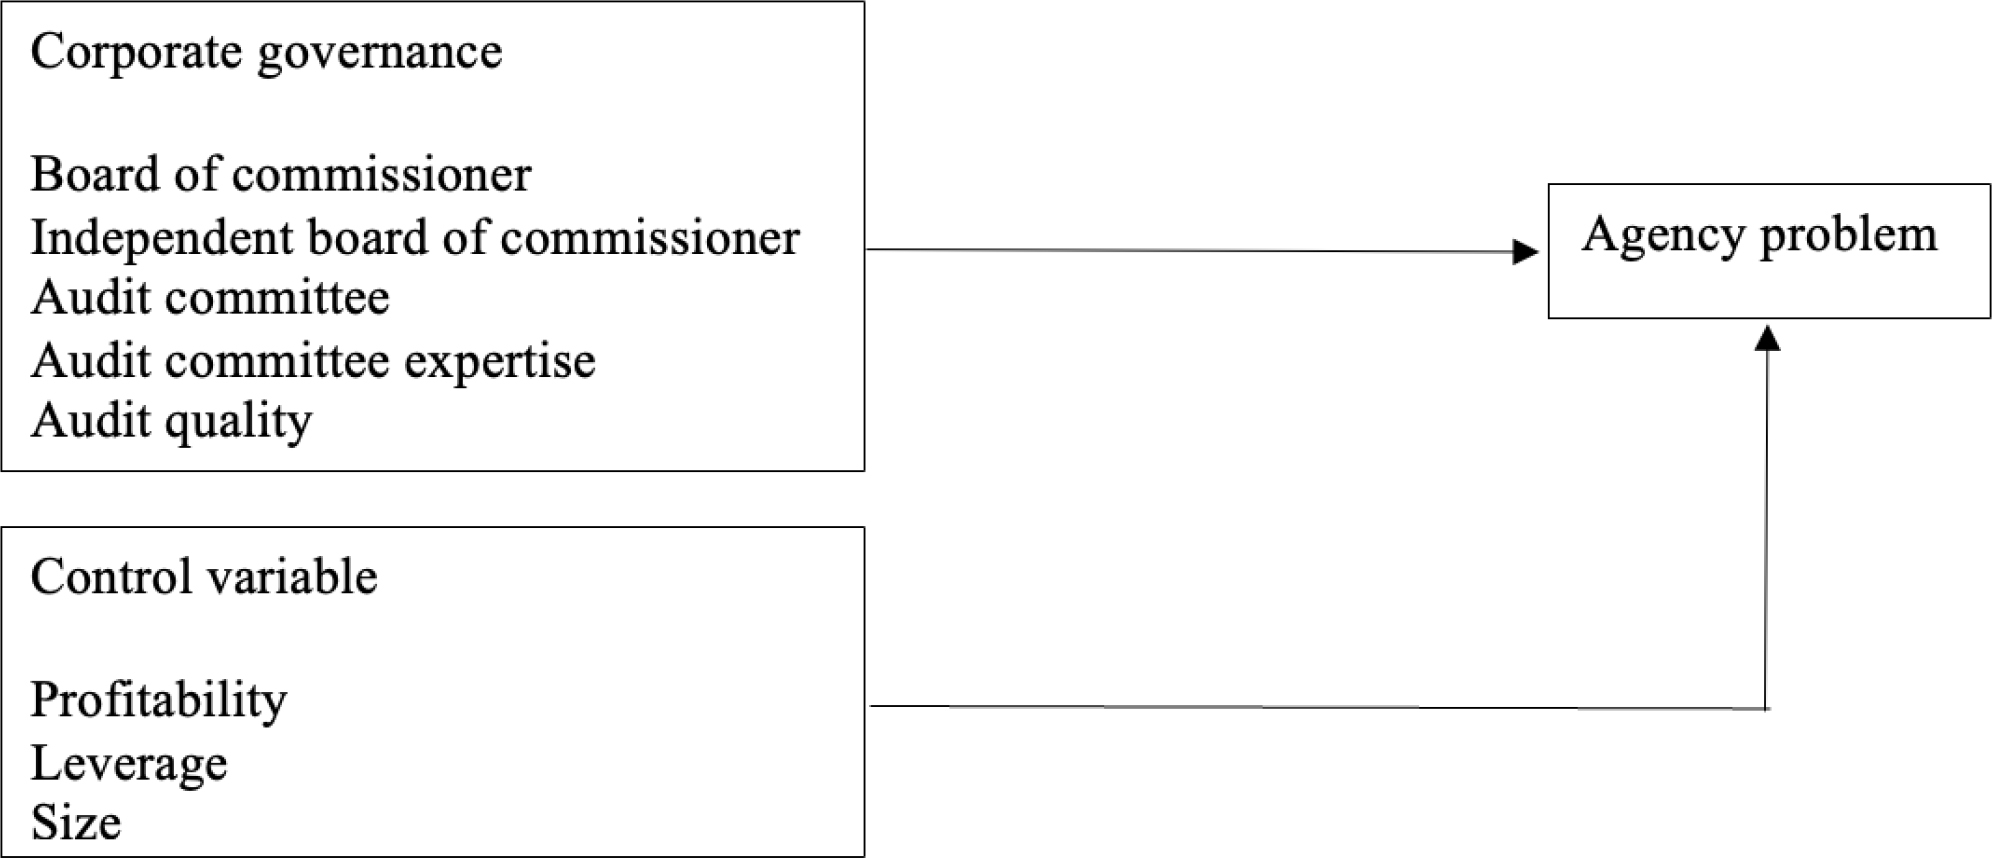
Figure 2.
Research Framework
(Source: Author’s own research)
Table 1.
Sample Selection Procedure (Source Author’s own research)
| No | Description | Total |
|---|---|---|
| 1. | During the research period, companies in the consumer cyclical and consumer non-cyclical sectors that were listed on the Indonesia Stock Exchange were examined. | 191 |
| 2. | Companies that do not present financial reports as of December 31 | (16) |
| 3. | Companies that do not to use the Rupiah currency | (13) |
| 4. | Companies that experience losses | (96) |
| Total number of companies | 66 | |
| Research period | 3 years | |
| Total number of samples | 198 | |
Table 2.
Variable Measurement (Source: Author’s own research)
| Variable | Definition | Measurement |
|---|---|---|
| Agency problem (AP) | Agency conflicts stem from misaligned incentives between the principal and the agent. In this study, agency conflicts are assessed through the lens of earnings management as proposed by Dechow in 1995. The evaluation of agency conflicts can be conducted by examining earnings management. Thus, this study aims to utilize framework for measuring earnings management. (Dechow, et al., 1995) | |
| Board of commissioners (BOC) | The board of commissioners serves as the overseeing body within a company that operates under a two-tier system. Its primary role is to supervise and offer guidance to the board of directors. | ∑ Number of commissioners |
| Independent commissioners (IND) | Independent commissioners are individuals serving on the board of commissioners without any ties to the company. | |
| Audit committee (AC) | The audit committee functions as an additional supervisory entity selected by the board of commissioners. | ∑ Number of audit committees |
| Audit committee expertise (EXP) | Audit committee members are chosen based on a specific criterion, which is possessing proficiency and practical knowledge in finance. | |
| Audit quality (AQ) | External auditors are individuals who are not affiliated with the company and are designated to ensure the reliability and accuracy of the financial statements. | Audit quality can be assessed by utilizing a binary variable, assigned a value of 1 when the external auditor of the company is affiliated with one of the Big 4 firms, and 0 otherwise. |
| Profitability (PROF) | The profitability of a company demonstrates its capacity to generate a net income | |
| Leverage (LEV) | Leverage refers to the assessment of the proportion of debt to equity within a company. | |
| Firm size (SIZE) | The size of a company is determined by the quantity of assets it possesses. As the number of assets owned increases, so does the magnitude of the company. | Natural logarithm (Total assets) |
Table 3.
Descriptive Statistics (Source: Author’s own research)
| Maximum | Minimum | Mean | Std. deviation | |
|---|---|---|---|---|
| AP | 0.8393 | - 0.2282 | 0.0045 | 0.1075 |
| BOC | 10 | 2 | 4.1818 | 1.6912 |
| IND | 0.8333 | 0.3333 | 0.4389 | 0.1141 |
| AC | 3 | 3 | 3.0151 | 0.1224 |
| EXP | 1 | 0 | 0.5795 | 0.2503 |
| AQ | 1 | 0 | 0.4595 | 0.4996 |
| PROF | 0.4930 | 0.0002 | 0.0799 | 0.0705 |
| LEV | 7.5853 | 0.0004 | 0.9304 | 0.9918 |
| SIZE | 259,692,979,111 | 180,433,300,000,000 | 14,557,693,746,764 | 27,683,481,766,119 |
Table 4.
Correlation Results (Source: Author’s own research)
| EM | BOC | IND | AC | EXP | AQ | PROF | LEV | SIZE | |
|---|---|---|---|---|---|---|---|---|---|
| AP | 1 | - | - | - | - | - | - | - | - |
| BOC | - 0.078 | 1 | - | - | - | - | - | - | - |
| IND | - 0.030 | - 0.130 | 1 | - | - | - | - | - | |
| AC | - 0.016 | 0.060 | 0.393 | 1 | - | - | - | - | - |
| EXP | - 0.186 | 0.202 | - 0.150 | - 0.163 | 1 | - | - | - | - |
| AQ | - 0.159 | 0.441 | - 0.022 | - 0.114 | 0.321 | 1 | - | - | - |
| PROF | 0.331 | 0.003 | 0.209 | - 0.124 | 0.215 | 0.146 | 1 | - | - |
| LEV | - 0.137 | 0.214 | 0.315 | 0.409 | 0.007 | 0.118 | - 0.134 | 1 | - |
| SIZE | 0.046 | 0.506 | 0.072 | - 0.111 | 0.176 | 0.470 | 0.058 | 0.157 | 1 |
Table 5.
Multicollinearity Results (Source: Author’s own research)
| Variable | VIF |
|---|---|
| BOC | 1.646 |
| IND | 1.522 |
| AC | 1.492 |
| EXP | 1.164 |
| AQ | 1.531 |
| PROF | 1.167 |
| LEV | 1.412 |
| SIZE | 1.620 |
Table 7.
Heteroskedasticity Results (Source: Author’s own research)
| F-statistic | 11.9135 | Prob. F | 0.0000 |
| Obs*R2 | 66.3754 | Prob. chi-square | 0.0000 |
Table 8.
Hypothesis Results (Huber-White) (Source: Author’s own research)
| Variable | Predicted Sign | Coefficient | t-Statistic | Prob. |
|---|---|---|---|---|
| Constanta | - | - 0.567556 | - 2.684904 | - |
| BOC | - | - 0.003839 | - 0.994104 | 0.3214 |
| IND | - | - 0.129492 | - 1.790326 | 0.0750* |
| AC | - | 0.072867 | 1.437175 | 0.1523 |
| EXP | - | - 0.105775 | - 3.045734 | 0.0027* |
| AQ | - | - 0.044776 | - 2.688230 | 0.0078* |
| PROF | -/+ | 0.660226 | 2.272222 | 0.0242* |
| LEV | -/+ | - 0.007082 | - 0.761935 | 0.4470 |
| SIZE | -/+ | 0.015775 | 3.365222 | 0.0009* |