

Table 1.
Theory to Hypothesis development
| Theory | Key mechanism in Kosovo | Linked hypothesis (section 2.4) | Regression variable(s) |
|---|---|---|---|
| Agency | Low litigation → muted risk pricing | H3 | CR |
| Signalling | Brand value under opacity | H4 | ‘BIG10’ |
| Regulation amplifies brand | H6 | ‘BIG10’ × POST2019 | |
| RBV | Capability demands of size/complexity | H1, H2 | CS, CC |
| Institutional voids | Weak enforcement blunts the CG effect | H5 | CGAF |
Table 2.
Variable definitions, theoretical link and expected sign
| Construct | Operational measure | Theoretical link | Expected sign |
|---|---|---|---|
| Audit Fee (LnAF) | Natural log of statutory audit fee (€) | Dependent variable | − |
| Client Size (CS) | Ln (Total Assets) | RBV | + |
| Client Complexity (CC) | Business segments, geographical divisions, or interactions between business units. | RBV | + |
| Client Risk (CR) | 3-point ordinal score (1 = Low, 2 = Medium, 3 = High) assigned annually by the engagement partner; criteria: distress, complexity, audit history. | Agency | + |
| Audit firm Size (‘BIG10’) | 1 = member of Big 10 network, else 0 | Signalling | + |
| Corporate Governance (CGAF) | 0–10 composite: Board Independence (0–4) + Audit-Committee Expertise (0–3) + Gender Diversity (0–3); recalculated each fiscal year. | Institutional voids | +/− |
| POST2019 | 1 for FY 2020–2022, else 0 | Regulatory shock | ± |
| ‘BIG10’ × POST2019 | Interaction term | H6 | + |
| Controls | Profitability (ROA), Auditor Tenure, Industry Specialisation dummies, Year FE. | — | var |
Table 3.
The results of the Cronbach's Alpha test
| N | % | ||
|---|---|---|---|
| Cases | Valid | 300 | 100.0 |
| Excluded | 0 | 0.0 | |
| Total | 300 | 100.0 | |
| Reliability Statistics (Test) | |||
| Cronbach's Alpha | Number of Items | ||
| 0.802 | 10 | ||
Table 4.
Descriptive Statistics
| Variables | N | Minimum | Maximum | Mean | Std. Deviation (SD) |
|---|---|---|---|---|---|
| Audited companies (sample) | 300 | 1 | 300 | 150.5 | 86.7 |
| Audit Fee | 300 | 900 | 640 | 3632 | 1411 |
| Client Size (CS) | 300 | 548,769.4 | 4,998,729.5 | 2,798,741.7 | 922,337.2 |
| Client Complexity (CC) | 300 | 1 | 5 | 2.8 | 1.19 |
| Client Risk (CR) | 300 | 1 | 5 | 3 | 1.2 |
| Audit Firm Size (‘BIG10’) | 300 | 0 | 1 | 0.48 | 0.50 |
| Corporate Governance of Audited Firms (CGAF) | 300 | 1 | 2.9 | 1.9 | 0.57 |
| Profitability of the Audited Company (PAC) | 300 | 1.1% | 49.92% | 25.69% | 13.98% |
| Auditor Tenure (TEN) | 300 | 1.0 | 9.0 | 4.9 | 2.54 |
| Industry Specialisation (IS) | 300 | 1 | 5 | 2.9 | 1.2 |
Table 5.
Correlation Analysis Results
| Variables | (1) | (2) | (3) | (4) | (5) | (6) | |
|---|---|---|---|---|---|---|---|
| Audit Fee (AF) (1) | Cor | 1 | 0.907** | 0.181** | 0.043 | 0.089 | 0.062 |
| Sig | 0.000 | 0.002 | 0.458 | 0.126 | 0.287 | ||
| N | 300 | 300 | 300 | 300 | 300 | 300 | |
| Client Size (CS) (2) | Cor | 0.907** | 1 | 0.067 | 0.037 | −0.084 | 0.052 |
| Sig | 0.000 | 0.250 | 0.529 | 0.148 | 0.369 | ||
| N | 300 | 300 | 300 | 300 | 300 | 300 | |
| Client Complexity (CC) (3) | Cor | 0.181** | 0.067 | 1 | −0.035 | −0.043 | 0.012 |
| Sig | 0.002 | 0.250 | 0.545 | 0.460 | 0.842 | ||
| N | 300 | 300 | 300 | 300 | 300 | 300 | |
| Client Risk (CR) (4) | Cor | 0.043 | 0.037 | −0.035 | 1 | 0.138* | −0.079 |
| Sig | 0.458 | 0.529 | 0.545 | 0.017 | 0.171 | ||
| N | 300 | 300 | 300 | 300 | 300 | 300 | |
| Audit Firm Size (‘BIG10’) (5) | Cor | 0.089 | −0.084 | −0.043 | 0.138* | 1 | −0.049 |
| Sig | 0.126 | 0.148 | 0.460 | 0.017 | 0.398 | ||
| N | 300 | 300 | 300 | 300 | 300 | 300 | |
| Corporate Governance of Audited Firms (CGAF) (6) | Cor | 0.062 | 0.052 | 0.012 | −0.079 | −0.049 | 1 |
| Sig | 0.287 | 0.369 | 0.842 | 0.171 | 0.398 | ||
| N | 300 | 300 | 300 | 300 | 300 | 300 |
Table 6.
Results of the Regression Analysis
| Audit fee | Coef. | St. Err. | t-value | p-value | [95% Conf | Interval] | Sig |
|---|---|---|---|---|---|---|---|
| CS | 0.001 | 0.01 | 42.79 | 0.000 | 0.01 | 0.03 | *** |
| CC | 151.71 | 25.04 | 6.06 | 0.000 | 102.4 | 200.9 | *** |
| CR | −6.96 | 23.64 | −0.29 | 0.768 | −53.4 | 39.5 | |
| ‘BIG10’ | 481.66 | 60.61 | 7.95 | 0.000 | 362.3 | 600.9 | *** |
| CGAF | 45.24 | 51.88 | 0.87 | 0.384 | −56.8 | 147.3 | |
| PAC | 215.21 | 214.48 | 1.00 | 0.316 | −206.9 | 637.3 | |
| TEN | 26.05 | 11.81 | 2.20 | 0.028 | 2.7 | 49.3 | ** |
| IS | 45.81 | 24.31 | 1.88 | 0.061 | −2.0 | 93.6 | * |
| ‘BIG10’ × POST2019 | 920.34 | 85.12 | 2.59 | 0.011 | 53.4 | 387.3 | *** |
| Constant | −77.43 | 198.58 | −0.39 | 0.697 | −468.2 | 313.4 | |
| Mean dependent var | 3632.000 | SD dependent var | 1411.080 | ||||
| R-squared | 0.879 | Number of obs | 300 | ||||
| F-test | 243.045 | Prob > F | 0.000 | ||||
| Akaike crit. (AIC) | 4607.977 | Bayesian crit. (BIC) | 4641.311 | ||||
Table 7.
Testing for Multicollinearity
| Variables | VIF | 1/VIF |
|---|---|---|
| ‘BIG10’ | 1.033 | .968 |
| CR | 1.03 | .97 |
| CS | 1.02 | .981 |
| CGAF | 1.015 | .985 |
| TEN | 1.014 | .986 |
| CC | 1.013 | .987 |
| IS | 1.01 | .99 |
| PAC | 1.01 | .991 |
| Mean VIF | 1.018 |
Table 8.
Testing for Heteroskedasticity
| Breusch-Pagan / Cook-Weisberg test for heteroskedasticity | Value |
|---|---|
| chi2(1) | 58.28 |
| Prob > chi2 | 0.6717 |
Table 9.
Distribution of the Data
| Variable | Obs | W | V | z | Prob>z |
|---|---|---|---|---|---|
| AF | 300 | 0.958 | 8.845 | 5.117 | .654 |
| CS | 300 | 0.944 | 11.997 | 5.832 | .860 |
| CC | 300 | 0.995 | 1.013 | 0.031 | .488 |
| CR | 300 | 0.993 | 1.411 | 0.808 | .209 |
| ‘BIG10’ | 300 | 1 | 0.104 | −5.308 | .999 |
| CGAF | 300 | 0.954 | 9.778 | 5.352 | .860 |
| PAC | 300 | 0.955 | 9.533 | 5.293 | .964 |
| TEN | 300 | 0.985 | 3.196 | 2.728 | .203 |
| IS | 300 | 0.997 | 0.68 | −0.906 | .817 |
Table 10.
Differences in Audit Fees Based on Client Complexity
| Client Complexity (CC) | Posterior | 95% Credible Interval | |||
|---|---|---|---|---|---|
| Mode | Mean | Variance | Lower Bound | Upper Bound | |
| Client Complexity (CC) = 1 | 3,439.4 | 3439.4 | 51,062.8 | 2,996.2 | 3,882.6 |
| Client Complexity (CC) = 2 | 3,429.8 | 3429.8 | 22,303.3 | 3,136.9 | 3,722.8 |
| Client Complexity (CC) = 3 | 3,522.7 | 3522.7 | 24,561.8 | 3,215.3 | 3,830.1 |
| Client Complexity (CC) = 4 | 3,757.1 | 3757.1 | 30,799.8 | 3,412.9 | 4,101.3 |
| Client Complexity (CC) = 5 | 4,409.0 | 44,09.0 | 58,799.6 | 3,933.4 | 4,884.6 |
| Audit fees | Sum of Squares | df | Mean Square | F | Sig. |
| Between Groups | 26,819,165.8 | 4 | 6,704,791.4 | 3.479 | .009 |
| Within Groups | 568,533,634.1 | 295 | 1,927,232.6 | ||
| Total | 595,352,800.0 | 299 | |||
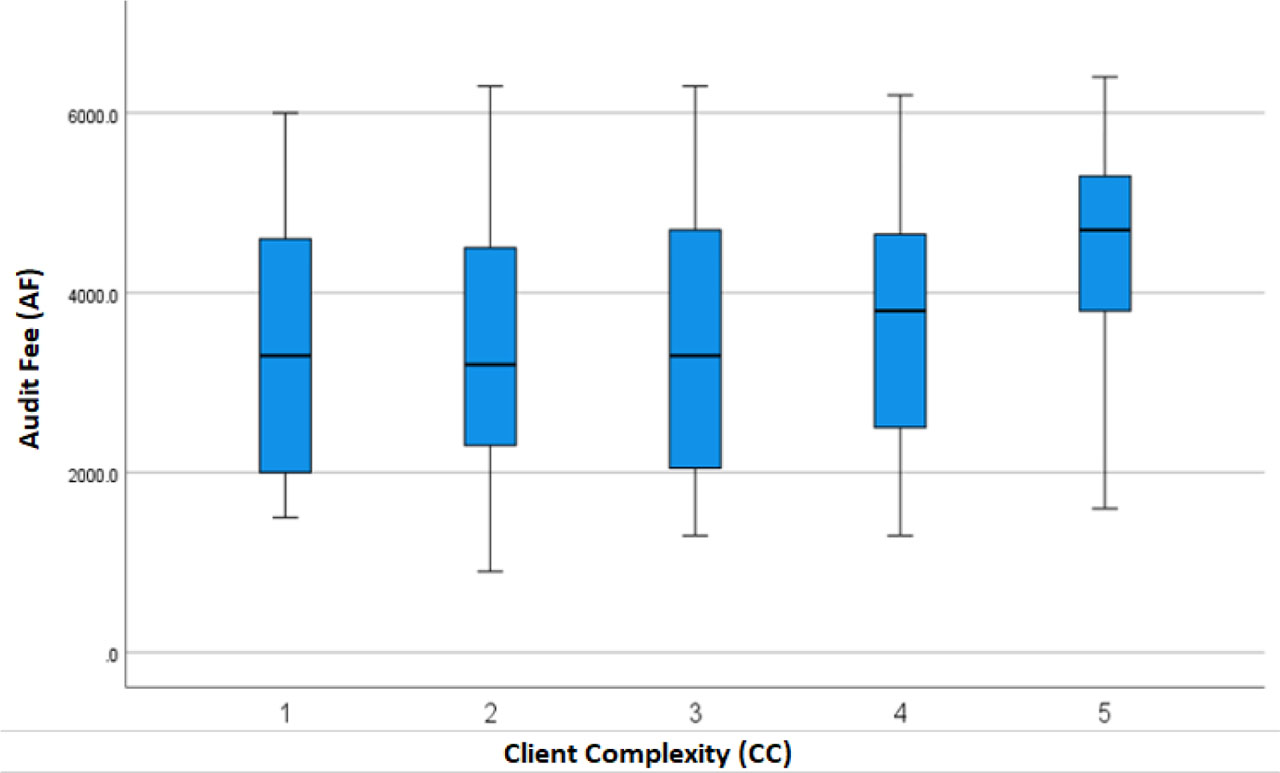
Figure 1.
Differences in Audit Fees Based on Client Complexity
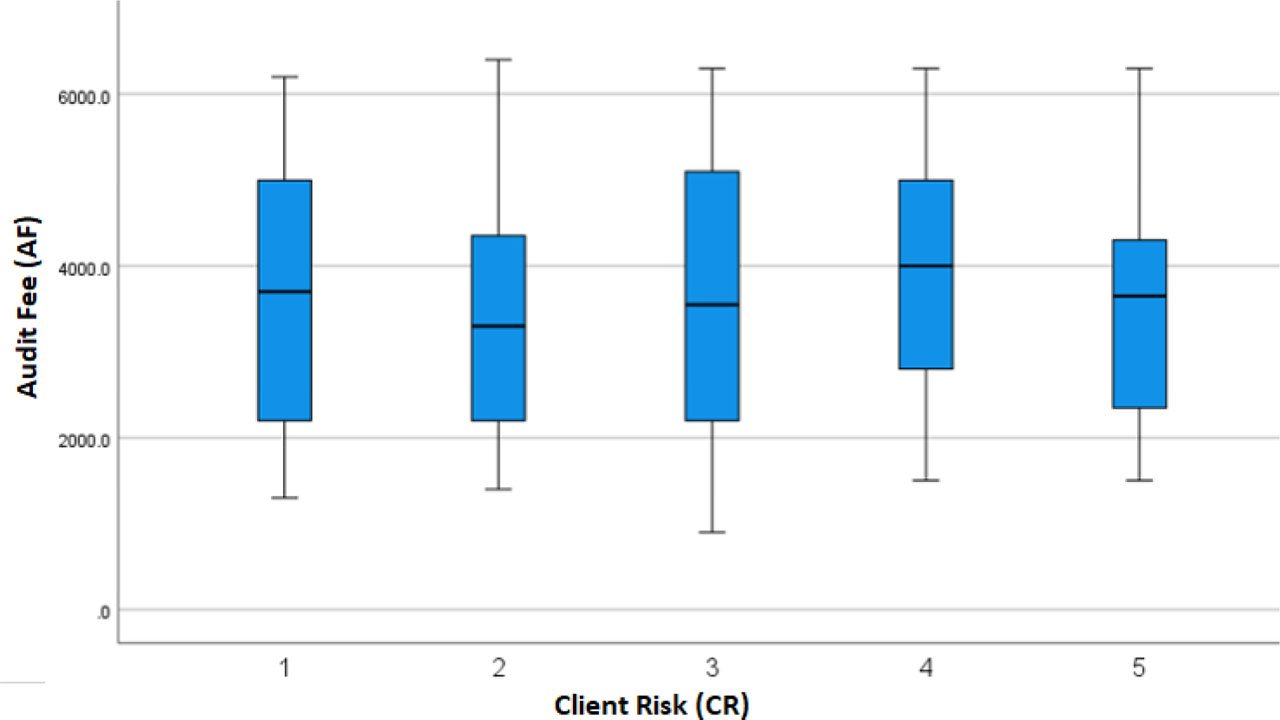
Figure 2.
Differences in Audit Fees Based on Client Risk
Source: authors' calculations (STATA).
Table 11.
Differences in Audit Fees Based on Client Risk
| Client Risk (CR) | Posterior | 95% Confidence Interval | |||
|---|---|---|---|---|---|
| Mode | Mean | Variance | Lower Bound | Upper Bound | |
| Client Risk (CR) = 1 | 3,695.5 | 3,695.5 | 44404.2 | 3,282.2 | 4,108.8 |
| Client Risk (CR) = 2 | 3,407.0 | 3,407.0 | 28143.5 | 3,078.5 | 3,736.8 |
| Client Risk (CR) = 3 | 3,571.8 | 3,571.8 | 31221.7 | 3,225.3 | 3,918.4 |
| Client Risk (CR) = 4 | 3,893.7 | 3,893.7 | 24977.3 | 3,583.7 | 4,203.7 |
| Client Risk (CR) = 5 | 3,532.5 | 3,532.5 | 49954.7 | 3,094.1 | 3,970.8 |
| Audit Fees | Sum of Squares | df | Mean Square | F | Sig. |
| Between Groups | 9,883,210.0 | 4 | 2,470,802.5 | 1.245 | .292 |
| Within Groups | 585,469,589.9 | 295 | 1,984,642.6 | ||
| Total | 595,352,800.0 | 299 | |||
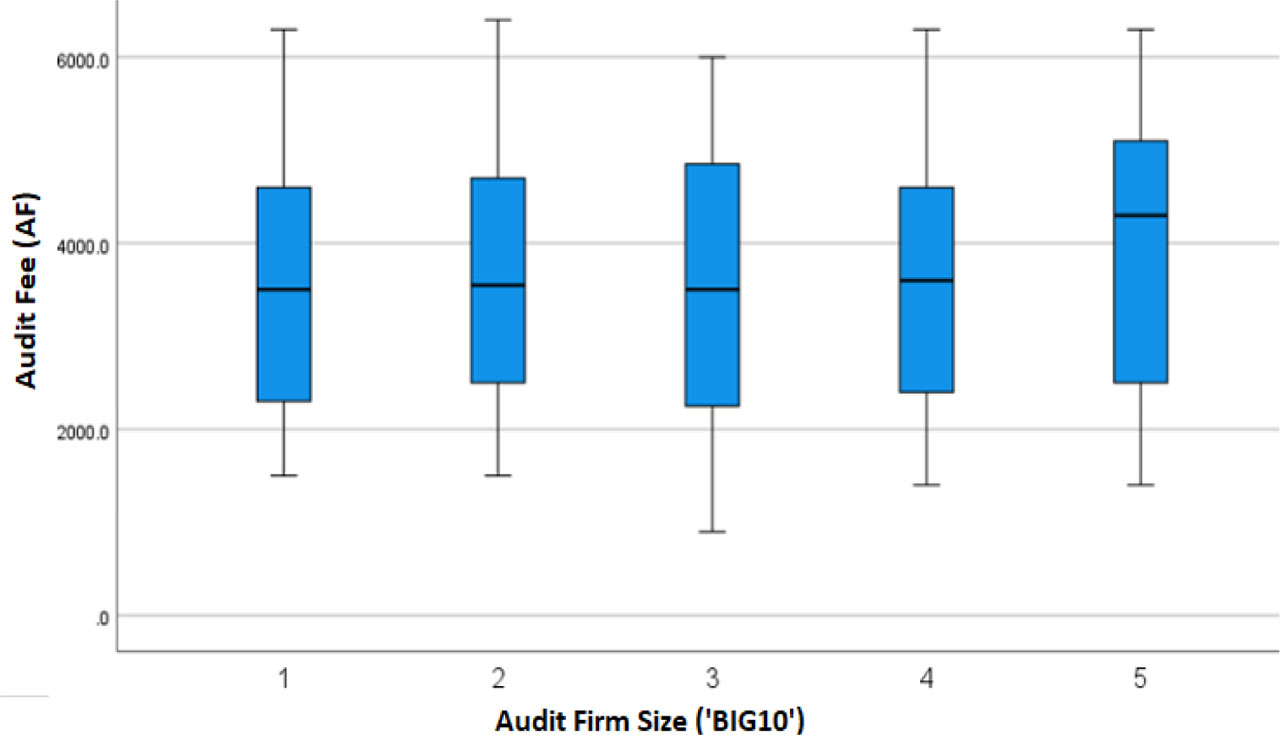
Figure 3.
Differences in Audit Fees Based on Audit Firm Size
Table 12.
Differences in Audit Fees Based on Audit Firm Size
| Audit Firm Size (‘BIG10’) | Posterior | 95% Confidence Interval | |||
|---|---|---|---|---|---|
| Mode | Mean | Variance | Lower Bound | Upper Bound | |
| Audit Firm Size (‘BIG10’) = 0 | 3,512.1 | 3,512.1 | 12,792 | 3,290.3 | 3,734 |
| Audit Firm Size (‘BIG10’) = 1 | 3,761.8 | 3,761.8 | 13,858 | 3,530.9 | 3,992.6 |
| Audit Fee (AF) | Sum of Squares | df | Mean Square | F | Sig. |
| Between Groups | 4,666,010.4 | 1 | 4,666,010.4 | 2.35 | 0.126 |
| Within Groups | 590,686,789.5 | 298 | 1,982,170.4 | ||
| Total | 595,352,800 | 299 | |||
Table 13.
Differences in Audit Fees Based on Industry Specialisation
| Industry Specialisation (IS) | Posterior | 95% Confidence Interval | |||
|---|---|---|---|---|---|
| Mode | Mean | Variance | Lower Bound | Upper Bound | |
| Industry Specialisation (IS) = 1 | 3,560.9 | 3,560.9 | 49,250.0 | 3,125.7 | 3,996.2 |
| Industry Specialisation (IS) = 2 | 3,644.2 | 3,644.2 | 28,846.4 | 3,311.1 | 3,977.4 |
| Industry Specialisation (IS) = 3 | 3,540.5 | 3,540.5 | 25,560.1 | 3,226.9 | 3,854.5 |
| Industry Specialisation (IS) = 4 | 3,619.1 | 3,619.1 | 27,661.0 | 3,292.9 | 3,945.3 |
| Industry Specialisation (IS) = 5 | 3,908.1 | 3908.1 | 54,574.4 | 3,449.9 | 4,366.3 |
| Audit Fees | Sum of Squares | df | Mean Square | F | Sig. |
| Between Groups | 3,711,426 | 4 | 927,856.6 | 0.463 | 0.763 |
| Within Groups | 5,916,413 | 295 | 2,005,563.9 | ||
| Total | 5,953,528 | 299 | |||
Table 14.
Summary of Hypothesis Testing
| H | Hypothesis | Coefficient | P-Value | Testing |
|---|---|---|---|---|
| 1 | A significant positive relationship exists between the size of the audited entity and audit fees in Kosovo. | β =0.001 | P=0.000 | Accepted |
| 2 | A significant positive relationship exists between the complexity of the audited entity and audit fees in Kosovo. | β=151.71 | P=0.000 | Accepted |
| 3 | There is a significant positive relationship between the risk of the audited entity and audit fees in Kosovo. | β=−6.96 | P=0.768 | Rejected |
| 4 | There is a significant positive relationship between large audit firms (‘Big-10’) and higher audit fees in Kosovo. | β=481.66 | P=0.000 | Accepted |
| 5 | Strong corporate governance is associated with lower audit fees in Kosovo. | β=45.24 | P=0.384 | Rejected |
| 6 | Regulatory moderation hypothesis: the positive association between ‘BIG10’ engagement and audit fees is stronger after the 2019 enactment of Law No. 06/L 032 than before (tested via an interaction term ‘BIG10’ × POST2019). | β=920.34 | P=0.011 | Accepted |
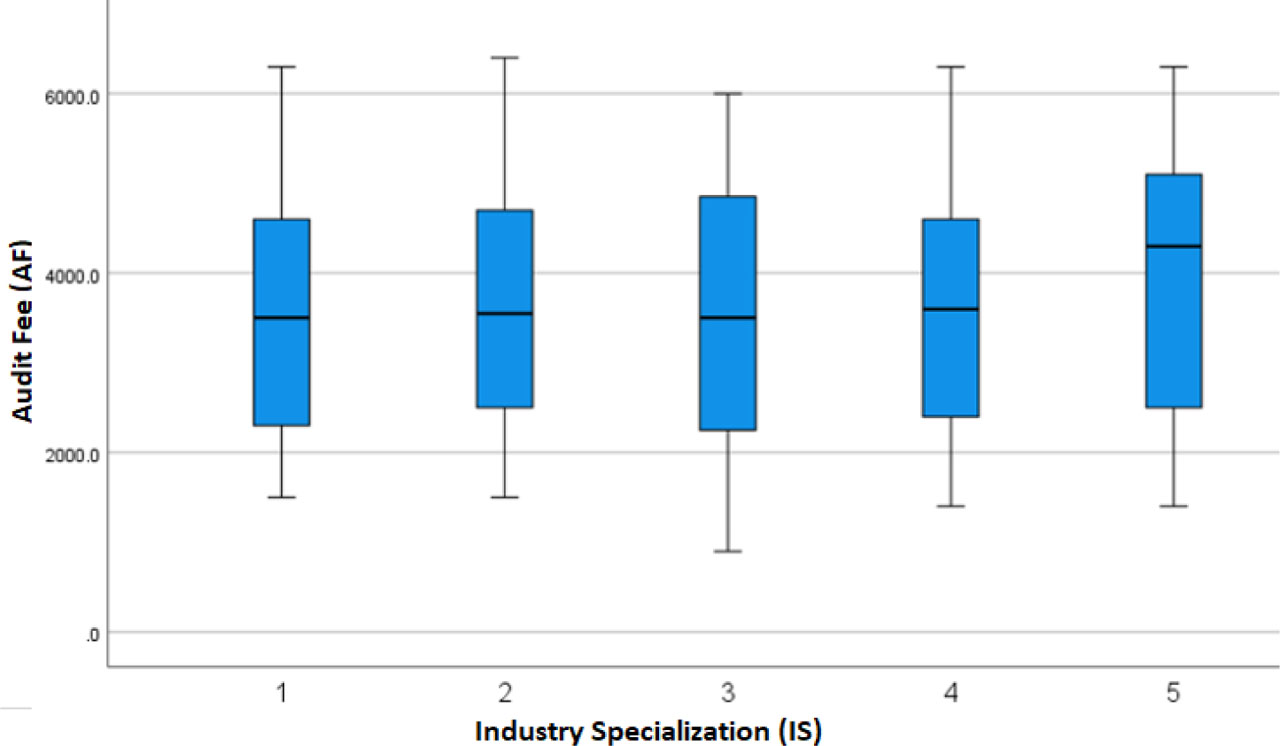
Figure 4.
Differences in Audit Fees Based on Industry Specialization
Table A1.
Sensitivity checks
| Model | Dep. Var. | Sample | ‘BIG10’ Coef. | CS Coef. | Adj. R2 |
|---|---|---|---|---|---|
| (1) Baseline OLS HC3 | LnAF | Full 300 | 481.7 *** | 0.00100 *** | 0.882 |
| (2) 2SLS (instrumented ‘BIG10’) | LnAF | Full 300 | 512.7 *** | 0.00102 *** | 0.871 |
| (3) Alt. dep. var. (Fee/Assets) | Fee/TA | Full 300 | 0.034 *** | 0.00080 *** | 0.425 |
| (4) Excluding ‘BIG10’ clients | LnAF | n = 252 | – | 0.00090 *** | 0.734 |
| (5) Year FE + CPI control | LnAF | Full 300 | 479.6 *** | 0.00101 *** | 0.889 |
| (6) Public firms only | LnAF | n = 15 | 620.3 ** | 0.00070 * | 0.793 |
Note: All 6 specifications deliver qualitatively almost identical inferences: the ‘BIG10’ coefficient remains large and highly significant (models 1–5, p < 0.01; model 6, p < 0.05), and Client Size (CS) always enters at 0.001 (p < 0.01). The 2SLS estimates in (2) rule out endogeneity bias in ‘BIG10’ choice, while the alternative fee metric (3), exclusion of ‘BIG10’ clients (4), and inclusion of year fixed effects plus CPI control (5) show the coefficients' stability. Even in the small public-only subsample (6), the ‘BIG10’ premium is larger, underscoring robustness across contexts
Table A2.
Split-sample by ownership type
| Sample | N | ‘BIG10’ Coef. | p-Value | CS Coef. | p-Value | Adj. R2 |
|---|---|---|---|---|---|---|
| Private companies | 285 | 467.8 *** | 0 | 0.00102 *** | 0 | 0.876 |
| Public companies | 15 | 620.3 ** | 0.014 | 0.00070 * | 0.083 | 0.793 |
Note: In the public firm subsample (n = 15), ‘BIG10’ engagement has an approximately 32% higher fee premium (€620 vs. €467; p = 0.014) than in privately held firms. This suggests that the signalling value of a Big 10 auditor is even more pronounced under the scrutiny of public market disclosure requirements. However, the smaller R2 and marginal CS significance (p = 0.083) caution against over-generalising from the limited public sample.