

Table 1.
Literature review on forecasting open-end investment fund NAV and performance using machine learning (chronological order)
| Author(s) | Year | Prediction objective | Dataset employed | Frequency of data | Machine learning prediction method | Error measures | Overall results |
|---|---|---|---|---|---|---|---|
| Chiang, Urban, Baldridge | (1996) | NAV p.s. | 1981–1986 101 US mutual funds | 5 years to predict year 6 | BPN vs regression models | MAPE | BPN model provided better predictions compared to regression models based on MAPE |
| Indro et al. | (1999) | 1-factor Jensen's alpha | 1993–1995 559 US equity funds | 3 years (1 year to predict 1 year) | MLP with GRG2 | ME, MAE, MAPE, MSE | MLP model outperformed other models based on multiple error measures |
| Lin et al. | (2007) | NAV p.s. | 3 single national equity funds of Taiwan, US and Japan | RBFNN | Error Index (EI) | RBFNN found effective | |
| Wang and Huang | (2010) | Sharpe index | 3 historical periods 1995–2000 Mutual funds listed in the Taiwan Economic Journal | 72 months (1 year to predict 1 year; every two years) | FANNC vs BPN | RMSE | FANNC model outperformed the BPN in terms of RMSE, providing more accurate predictions |
| Yan et al. | (2010) | NAV p.s. | 1 equity Chinese investment fund | BPN | good prediction accuracy | ||
| Ray and Vina | (2011) | NAV p.s. | 1999–2004 10 funds from India | 60 months | BPN | BPN demonstrated strong performance in predicting fund values | |
| Priyadarshini and Babu | (2012) | NAV p.s. | 2003–2009 1 fund | 84 months | BPN | MAE, MSE, RMSE, MAPE, MPE | Error measures indicate solid performance of the BNP model |
| Priyadarshini | (2015) | NAV p.s. | 2006–2012 1 fund | 72 months | MLP | MAE, MSE, MAPE, RMSE, MPE | Good predictive performance based on these error metrics |
| Narula, Jha, Panda | (2015) | NAV p.s. | 15-Oct-2012 till 2-Jan-2014; 200 Indian funds | 300 consecutive trading days | FLANN vs RBF vs MLP | MAPE | FLANN performed well according to MAPE |
| Anish and Majhi | (2016) | NAV p.s. | RBF and FLANN | MAPE, RMSE | both models performed well, with FLANN having a slight advantage in terms of MAPE and RMSE | ||
| Anish, B. Majhi, R. Majhi | (2018) | NAV p.s. | RBF-PSO in comparison to MLANN, FLANN and RBFNN | MAPE, RMSE | The RBF-PSO model was the most accurate according to MAPE and RMSE | ||
| Han et al. | (2018) | NAV p.s. | 31-Aug-2015 till 1-Jul-2016 2 funds | 210 days | GRNN | RMSE, RTIC, MAE, MAPE, CE | GRNN provides highly accurate predictions |
| Pan et al. | 2019 | NAV p.s. | 31-Aug-2015 till 1-Jul-2016 17 balanced open-end funds | 210 days | BPN vs GABPN vs multiple regression | RMSE, RTIC, MAE, MAPE, CE | BPN model showed superior performance |
| Das et al. | (2020) | SBI Magnum Equity and UTI Equity | 2010 | BPN, RBPNN, RRBFNN | MSE, RMSE, MAPE | RBPNN outperformed over the other two prediction methods | |
| Rout, Koudjonou, Satapathy | (2020) | NAV p.s. (normalized) | 1998–2002 5 equity funds | 1065–1255 days (80% of days in training and 20% of days in testing) | FLANN | RMSE, MAPE | FLANN found effective |
| Li and Rossi | (2020) | Carhart (1997) 4-factor adjusted alpha | 1980–2018 2980 US equity funds | 10 years of training to predict 1 subsequent year alpha | BRT, lasso, elastic net, random forest, NN | MAE, MSE, RMSE | Especially BRT and random forest outperform traditional regression models in predicting fund performance |
| Kaniel et al. | (2023) | 4/5/6/8-factor Jensen's alpha | 1980–2019 3275 U.S. equity funds | last month or year data to predict the next month | FFN | MAE | FFN models provided accurate predictions |
| DeMiguel et al. | (2023) | 6-factor Jensen's alpha | 1980–2020 8767 US equity funds | 10 years of training to predict 1 year alpha | Gradient boosting: random forest, elastic net | MAE, MSE, RMSE | these advanced machine learning models performed well in prediction accuracy over long training periods. |
[i] BPN – Backpropagation Neural Network; BRT - Boosted Regression Trees; CE – Coeficient Coefficiency; FANNC – Fast Adaptive Neural Network Classifier; FFN – Feedforward Neural Network; FLANN – Functional Link Artificial Neural Network; GABPN – Genetic Algorithm Backpropagation Neural Network; GRNN – General Regression Neural Network, NN – Neural Networks; RBPNN - Recurrent Back Propagation Neural Network; RRBFNN – Recurrent Radial Basis Function Neural Network
Table 2.
Descriptive statistics of studied funds (annualised logarithmic rate of returns)
| No. of funds | Avg NAV (in Mio PLN) | logarithmic return | |||||||
|---|---|---|---|---|---|---|---|---|---|
| max | min | avg | median | st.dev. | 1st quartile | 3rd quartile | |||
| all | 71 | 769.5 | 775% | −447% | 4.1% | 3.9% | 11.9% | −7.1% | 16.8% |
| equity funds | 18 | 602.72 | 443% | −447% | 3.9% | 4.6% | 19.6% | −30.7% | 43% |
| hybrid funds | 24 | 714.35 | 775% | −283% | 4.7% | 5.2% | 10.7% | −11.1% | 22.1% |
| fixed-income funds | 21 | 658.46 | 231% | −92% | 4.2% | 3.8% | 4.9% | −1% | 9.6% |
| money market fund | 8 | 906.68 | 44% | −70% | 3.8% | 3.6% | 1.5% | 2.2% | 5.2% |
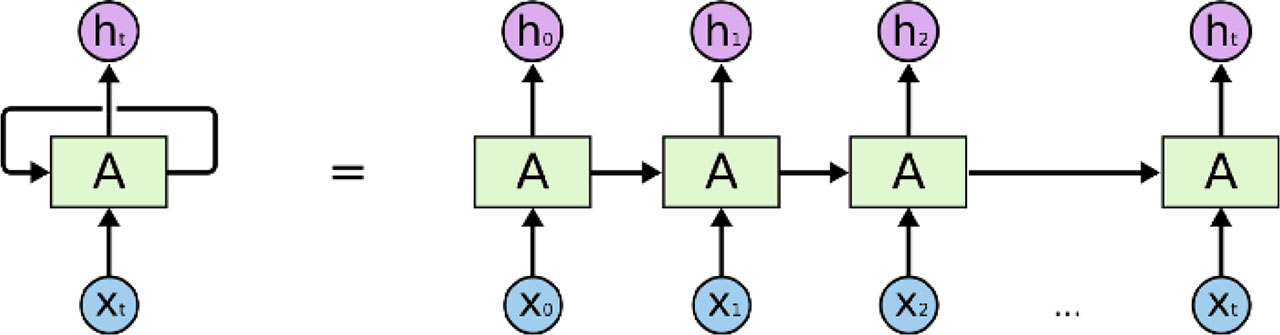
Figure 1.
RNN operation diagram
Source: (Olah, 2015)
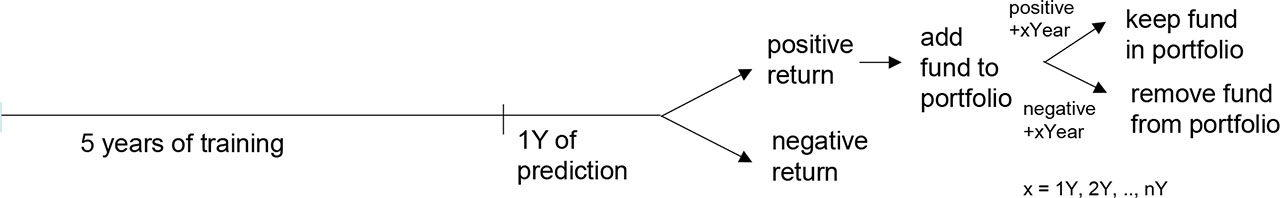
Figure 2.
Procedure for managing a portfolio of winning funds
Source: own figure
Table 3.
Returns of the strategy and its benchmarks
| average return | return for the best fund | return for the worst fund | |
|---|---|---|---|
| All funds | |||
| Strategy based on RNN fund return predictions | 34.12% | 245,76% | −29,67% |
| ARIMA model | 30.88% | 241.03% | −28,65% |
| “buy and hold” strategy | 30.44% | 241.03% | −30.22% |
| Equity funds | |||
| Strategy based on RNN fund return predictions | 33.74% | 85.21% | −28.88% |
| ARIMA model | 29.14% | 84.36% | −31.22% |
| “buy and hold” strategy | 29.47% | 84.36% | −30.22% |
| Hybrid funds | |||
| Strategy based on RNN fund return predictions | 36.29% | 246.54% | −16.95% |
| ARIMA model | 32.12% | 242.37% | −17.41% |
| “buy and hold” strategy | 31.96% | 241.03% | −17.68% |
| Fixed-income funds | |||
| Strategy based on RNN fund return predictions | 33.25% | 56.21% | 17.03% |
| ARIMA model | 31.01% | 54.90% | 16.49% |
| “buy and hold” strategy | 31.58% | 54.90% | 16.49% |
| Money market funds | |||
| Strategy based on RNN fund return predictions | 27.21% | 38.12% | 20.12% |
| ARIMA model | 24.98% | 37.51% | 18.77% |
| “buy and hold” strategy | 25.09% | 37.51% | 19.88% |