

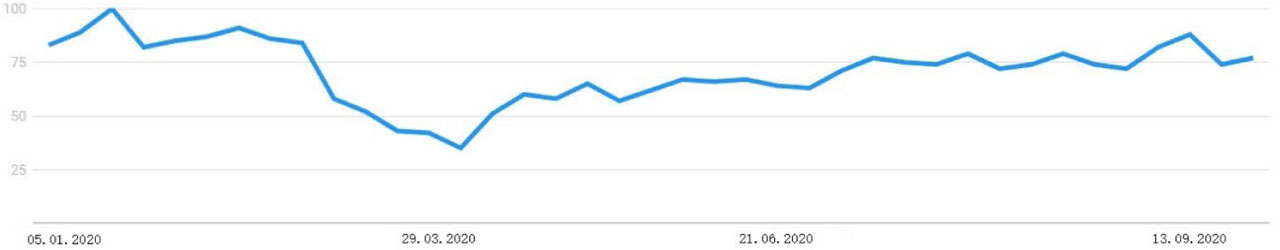
Figure 1
Indicator of “apartments for sale” queries directed to the Google search engine
Source: Google Trends, website: https://trends.google.pl/trends/explore?q=mieszkania%20na%20sprzeda%C5%BC&geo=PL [accessed: 10.10.2020.].
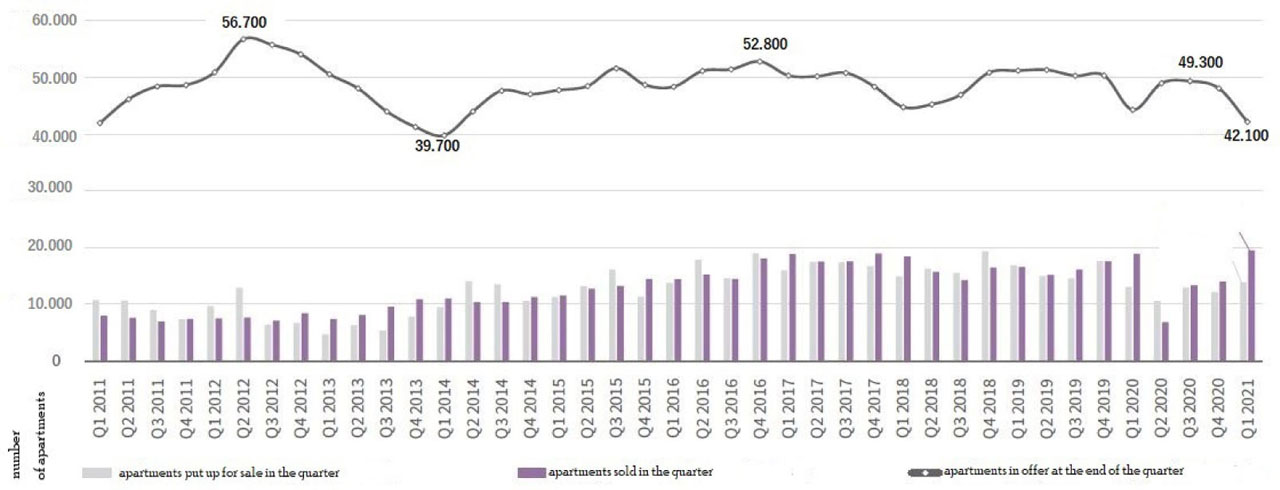
Figure 2
Quarterly relation of demand to supply – primary market
Source: JLL report, Rynek mieszkaniowy w Polsce Q1 2021 [‘Residential market in Poland Q1 2021’], p. 5.
Table 1
Dynamics q / q m2 prices of apartments in the analysed cities in Q2 2020
| RPO | RPT | RWO | RWT | |
|---|---|---|---|---|
| Gdańsk | −1.0% | −0.1% | −2.2% | 2.4% |
| Gdynia | 2.1% | −3.4% | −0.2% | 0.5% |
| Kraków | 5.7% | 4.3% | 1.6% | 3.8% |
| Łódź | −1.5% | −2.7% | −0.6% | 4.7% |
| Poznań | 2.9% | 0.2% | 0.2% | 3.3% |
| Wrocław | 2.0% | −3.8% | −1.6% | 2.5% |
| Warszawa | 1.0% | −3.9% | −1.2% | 0.2% |
| 6 cities | 2.2% | 0.3% | −0.4% | 3.5% |
| 10 cities | 3.6% | −1.2% | 2.4% | 4.5% |
[i] Source: Report: Informacja o cenach mieszkań i sytuacji na rynku nieruchomości mieszkaniowych i komercyjnych w Polsce w II kwartale 2020 r. [‘Information on flat prices and the situation on the residential and commercial real estate market in Poland in Q2 2020’], NBP, 2020, p. 1.
Table 2
Dynamics q / q m2 prices of apartments in the analysed cities in Q3 2020
| RPO | RPT | RWO | RWT | |
|---|---|---|---|---|
| Gdańsk | −1.7% | −3.3% | −0.7% | 4.4% |
| Gdynia | 1.4% | 3.3% | 1.4% | 2.7% |
| Kraków | −2.8% | 2.0% | −1.3% | 0.5% |
| Łódź | 3.4% | 5.4% | 0.6% | 7.0% |
| Poznań | 2.0% | 0.3% | 0.4% | 2.4% |
| Wrocław | 0.2% | 0.9% | 3.5% | −2.6% |
| Warszawa | 0.2% | 7.9% | 1.7% | −3.0% |
| 6 cities | 0.2% | 1.9% | 0.4% | 2.5% |
| 10 cities | 3.3% | 2.7% | 0.6% | 0.2% |
[i] Source: Report: Informacja o cenach mieszkań i sytuacji na rynku nieruchomości mieszkaniowych i komercyjnych w Polsce w III kwartale 2020 r. [‘Information on flat prices and the situation on the residential and commercial real estate market in Poland in Q3 2020’], NBP, 2020, p. 1.
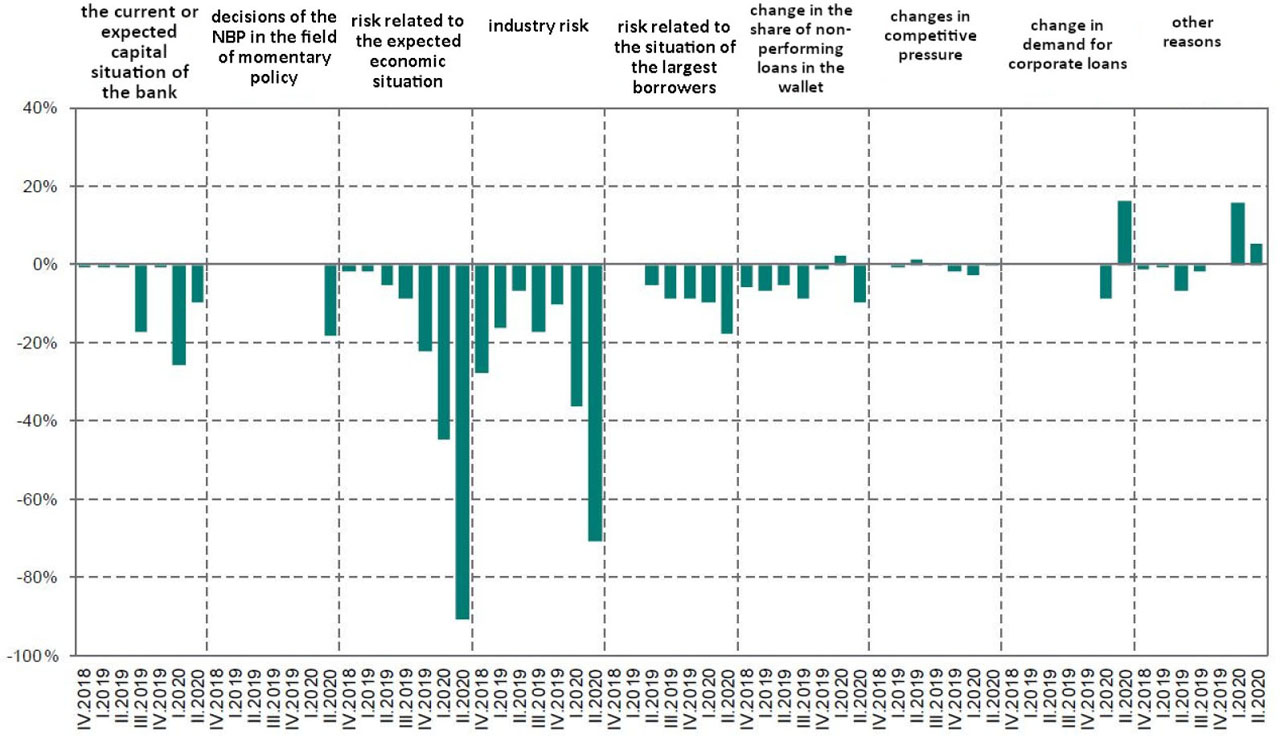
Figure 3
Reasons for changes in lending policy – home loans
Source: Report: Sytuacja na rynku kredytowym - wyniki ankiety do przewodniczących komitetów kredytowych, III kwartał 2020 r. [Situation on the credit market – results of the survey to chairmen of credit committees, Q3 2020], Departament Stabilności Finansowej [Financial Stability Department], p. 8.
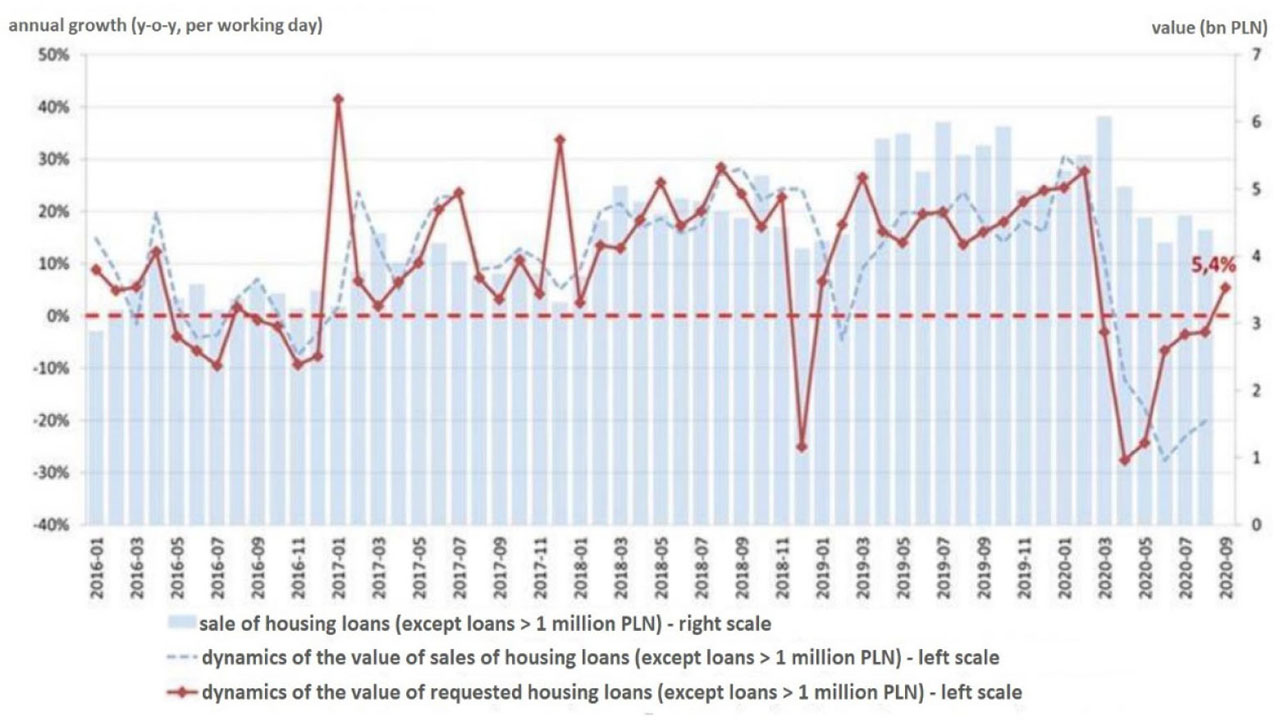
Figure 4
BIK index – the demand for housing loans
Source: BIK (Credit Reporting Service), media.bik.pl/informacje-prasowe/578007/bik-indeks-popytu-na-kredyty-mieszkaniowe-wyniosl-we-wrzesniu-2020-r-5-4 [accessed: 07.10.2020].
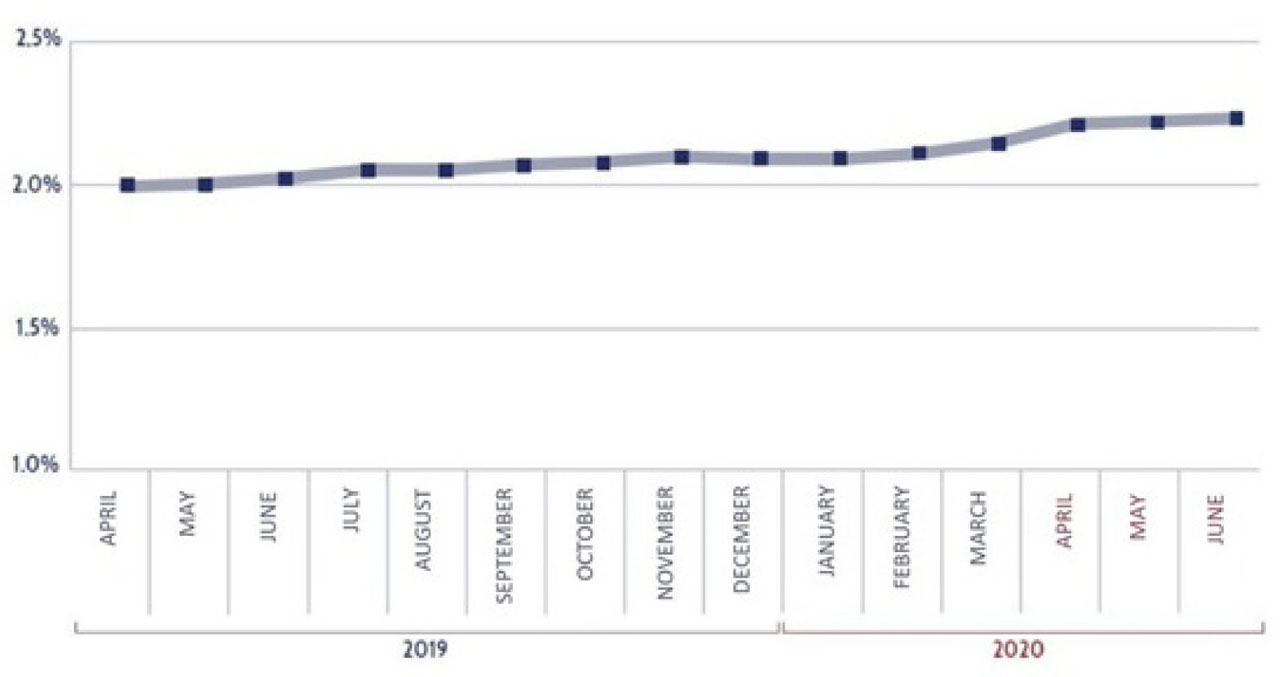
Figure 5
Average mortgage loan margin (%)
Source: AMRON-SARFiN report, Ogólnopolski raport kredytach mieszkaniowych i cenach transakcyjnych nieruchomości [Polish nationwide report on housing loans and property transaction prices], 2/2020, p. 16.
Table 3
Comparison of mortgage loans offers
| Month | |||
|---|---|---|---|
| February | April | September | |
| Simulation name | Citi Handlowy Housing Loan for the Priority segment Margin 1.74 | Citi Handlowy Housing Loan for the Priority segment Margin 1.74 | Citi Handlowy Housing Loan for the Priority segment Margin 1.89 |
| Monthly costs (from the second month) | 1357 PLN | 1268 PLN | 1153 PLN |
| Total cost of the loan | 192.198 PLN | 160.137 PLN | 118.704 PLN |
| Real interest | 3.8% | 3.23% | 2.46% |
| Bank margin | 1.74% | 1.74% | 1.89% |
| Reference rate | 1.71% | 1.17% | 0.28% |
[i] Source: Author's own analysis based on Ranking kredytów hipotecznych [‘Mortgage loan ranking’] https://marciniwuc.com/ranking-kredytow-hipotecznych/ [accessed 9.10.2020.].
Table 4
Own contribution in February, June and September
| Bank name | Own contribution (%) | ||
|---|---|---|---|
| February 2020 | June 2020 | September 2020 | |
| Alior Bank | 10% | 10% | 10% |
| BNP Paribas | 20% | 20% | 20% |
| BOŚ Bank | 20% |  30% | 30% |
| Credit Agricole | 10% | 10% | 10% |
| ING Bank Śląski | 20% | 30% |  20% |
| mBank | 10% | 20% | 10% |
| Bank Millennium | 10% | 10% | 10% |
| Pekao Bank Hipoteczny | 10% | 20% | 20% |
| Pekao SA | 10% | 15% | 15% |
| PKO BP | 10% | 20% | 20% |
| Bank Pocztowy | 20% | 20% | 20% |
| Santander | 10% | 20% | 10% (bank customers)/20% (external) |
[i] Source: Author's own analysis based on: Serafin A., Jak obliczyć wkład własny 2020? Wymagania banków przy kredycie hipotecznym [‘How to calculate the own contribution in 2020? Bank requirements for a mortgage loan’], https://direct.money.pl/artykuly/porady/jak-obliczyc-wklad-wlasny-2020-wymagania-bankow-przy-kredycie-hipotecznym.html [accessed 11.10.2020.] and Marszałek D., Kredyt hipoteczny a koronawirus - czy banki zmienią procedury i zaostrzą kryteria udzielania kredytów? [‘Mortgage loan and the coronavirus – will banks change procedures and tighten credit standards’], https://www.totalmoney.pl/artykuly/kredyt-hipoteczny-a-koronawirus-czy-banki-zmienia-procedury-i-zaostrza-kryteria-udzielania-kredytow [accessed 11.10.2020.].
Table 5
The structure of the LtV ratio for newly granted loans
| LtV ratio (%) | Q2 2019 | Q3 2019 | Q4 2019 | Q1 2020 | Q2 2020 |
|---|---|---|---|---|---|
| Up to 30% | 14.63% | 14.94% | 15.67% | 16.51% | 15.11% |
| Between 30% and 50% | 6.16% | 6.25% | 6.05% | 5.95% | 7.37% |
| Between 50% and 80% | 36.93% | 35.93% | 36.25% | 36.47% | 38.91% |
| From 80% | 43.09% | 42.88% | 42.03% | 41.07% | 38.61% |
[i] Source: AMRON-SARFiN report, Ogólnopolski raport o kredytach mieszkaniowych i cenach transakcyjnych nieruchomości [‘Polish nationwide report on housing loans and real estate transaction prices’], 2/2020, p. 12.
Table 6
Summary of negative and positive effects of the COVID-19 pandemic for borrowers
| No. | Positive effects | Negative effects |
|---|---|---|
| 1. | Limiting consumer spending of households | Uncertainty – difficulties in forecasting |
| 2. | Stable prices of residential real store | Fall in supply of housing |
| 3. | Stable level of the Housing Accessibility Index | Deterioration in the economic situation of households |
| 4. | Decline in demand for housing (less competition, grater negotiation opportunities on the market) | Tightening the criteria for granting loans by banks (including in terms of own contribution, margin, maximum possible loan amount, exclusion from financing of industries particularly exposed to insolvency) |
| 5. | Easing the lending policy (drop in interest rates, statutory and non-statutory credit holidays) | Extended waiting time for the funding decision |
| 6. | Lowering total credit costs for new loans | There are no uniform credit moratoria standards for all banks |
| 7. | Improving remote customer service |
[i] Source: own work.