

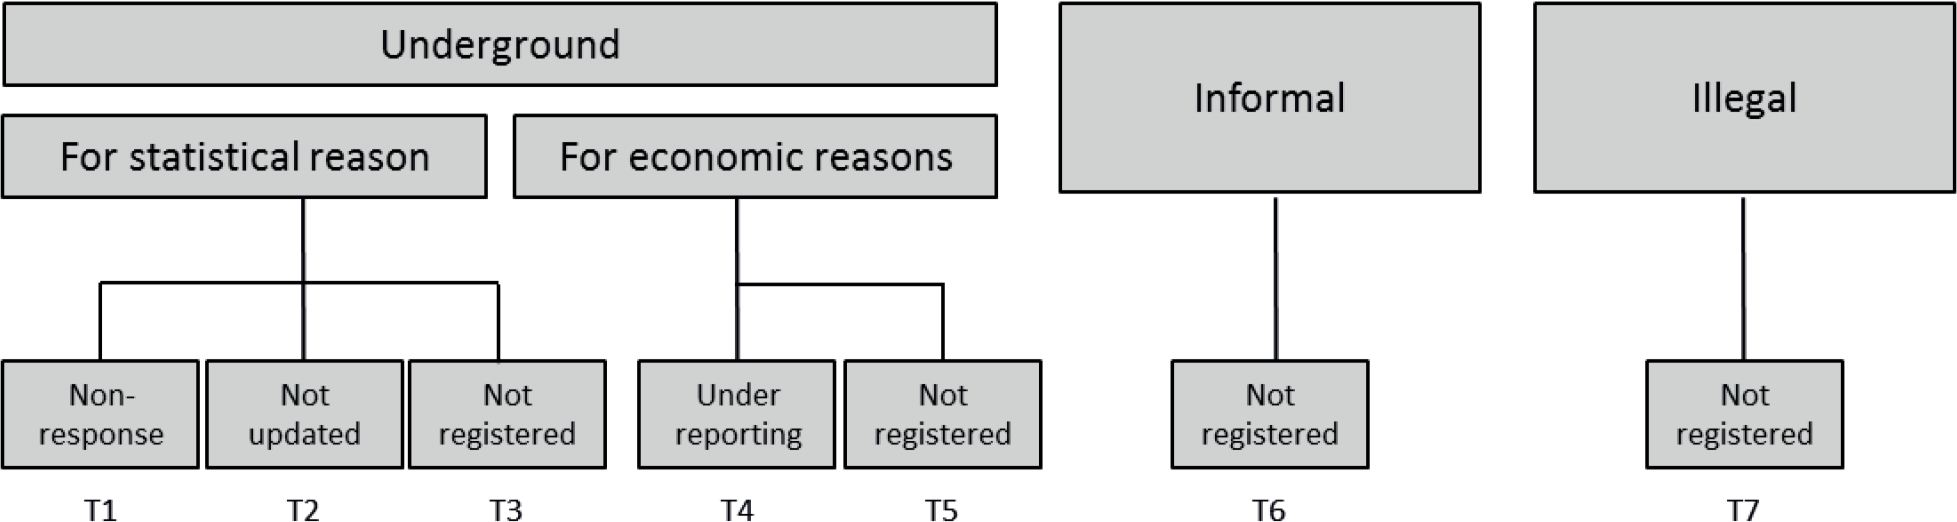
Fig. 1
The ISTAT framework for exhaustiveness.
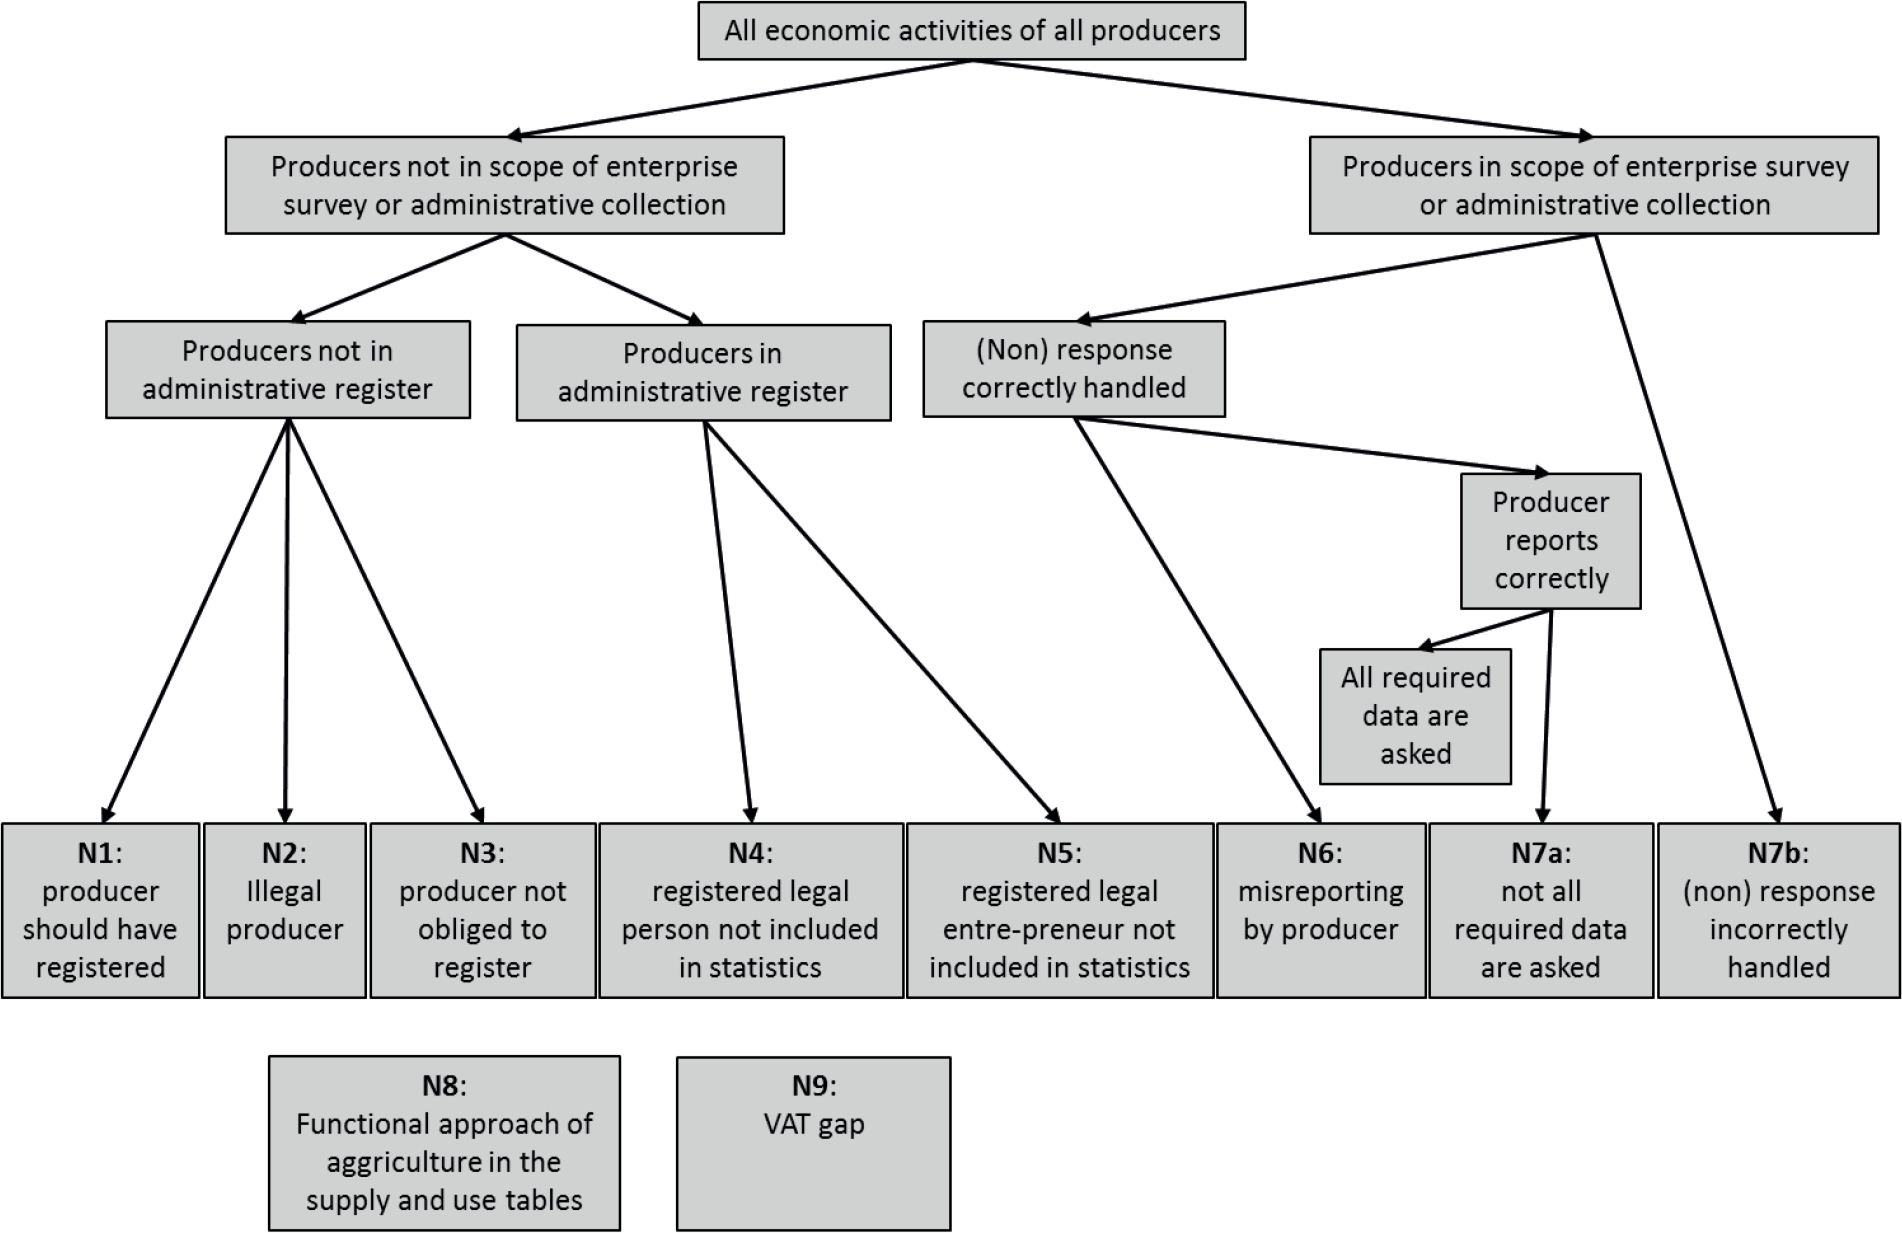
Fig. 2
Types of inexhaustiveness.
Tab. 1
Proposed estimate for fraud as percentage of total national income, 1920–1938
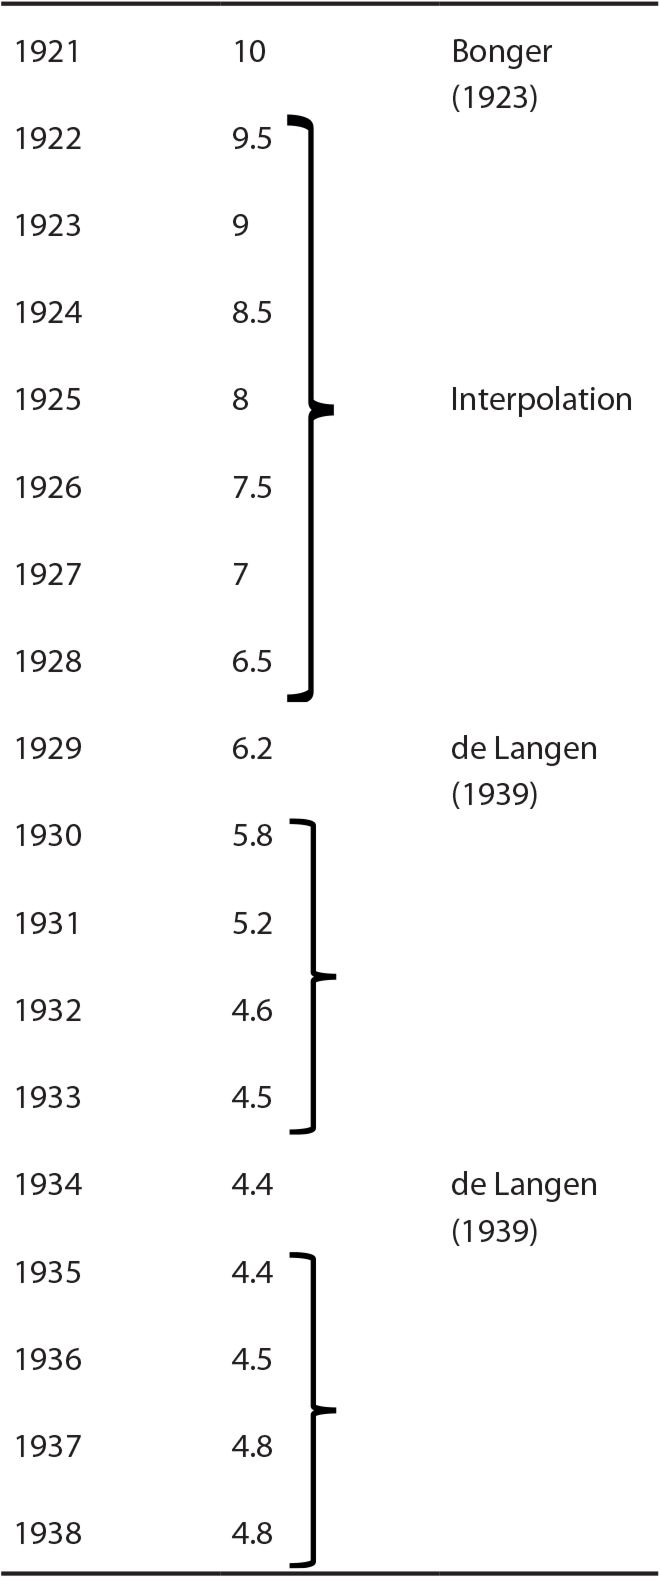
[i] Source: Archive Statistics Netherlands.
Tab. 2
Overview of estimates made for exhaustiveness, 2015
| Type | Production | Intermediate consumption | Value added | |
|---|---|---|---|---|
| Million euros | ||||
| House renovations and maintenance | N1 | 1,485 | 743 | 742 |
| Car repair and maintenance | N1 | 213 | 56 | 157 |
| Food/beverage service activities | N1 | 280 | 49 | 231 |
| Hairdressers and landscaping | N1 | 560 | 54 | 506 |
| Cleaning homes and other buildings | N1 | 1,337 | 0 | 1,337 |
| Babysitters and childcare | N1 | 316 | 0 | 316 |
| Other | N1 | 373 | 11 | 362 |
| Subtotal | N1 | 4,564 | 913 | 3,651 |
| Cannabis | N2 | 4,053 | 1,137 | 2,916 |
| Ecstasy, heroin, cocaine, etc. | N2 | 680 | 59 | 621 |
| Smuggling cigarettes | N2 | 115 | 12 | 103 |
| Fencing | N2 | 373 | 37 | 336 |
| Temporary employment mediation | N2 | 316 | 16 | 300 |
| Illegal copying and illegal gambling | N2 | 218 | 35 | 183 |
| Prostitution | N2 | 607 | 214 | 393 |
| Adjustment for double counting | –512 | –421 | –91 | |
| Subtotal | N2 | 5,850 | 1,089 | 4,761 |
| Own account construction | N3 | 208 | 151 | 57 |
| Tips | N3 | 567 | 0 | 567 |
| Own account energy production | N3 | 176 | 0 | 176 |
| Renting of dwellings | N3 | 164 | 50 | 114 |
| Other | N3 | 12 | 7 | 5 |
| Subtotal | N3 | 1,127 | 208 | 919 |
| Cost fraud | N6 | 0 | –763 | 763 |
| Subtotal | N6 | 0 | –763 | 763 |
| Income in kind | N7a | 158 | –4,869 | 5,027 |
| Functional approach of agriculture | N8 | –1,839 | –1,327 | –512 |
| VAT gap | N9 | 0 | –970 | 970 |
| Subtotal | N7a–N9 | –1,681 | –7,166 | 5,485 |
| Total | 9,860 | –5,719 | 15,579 |
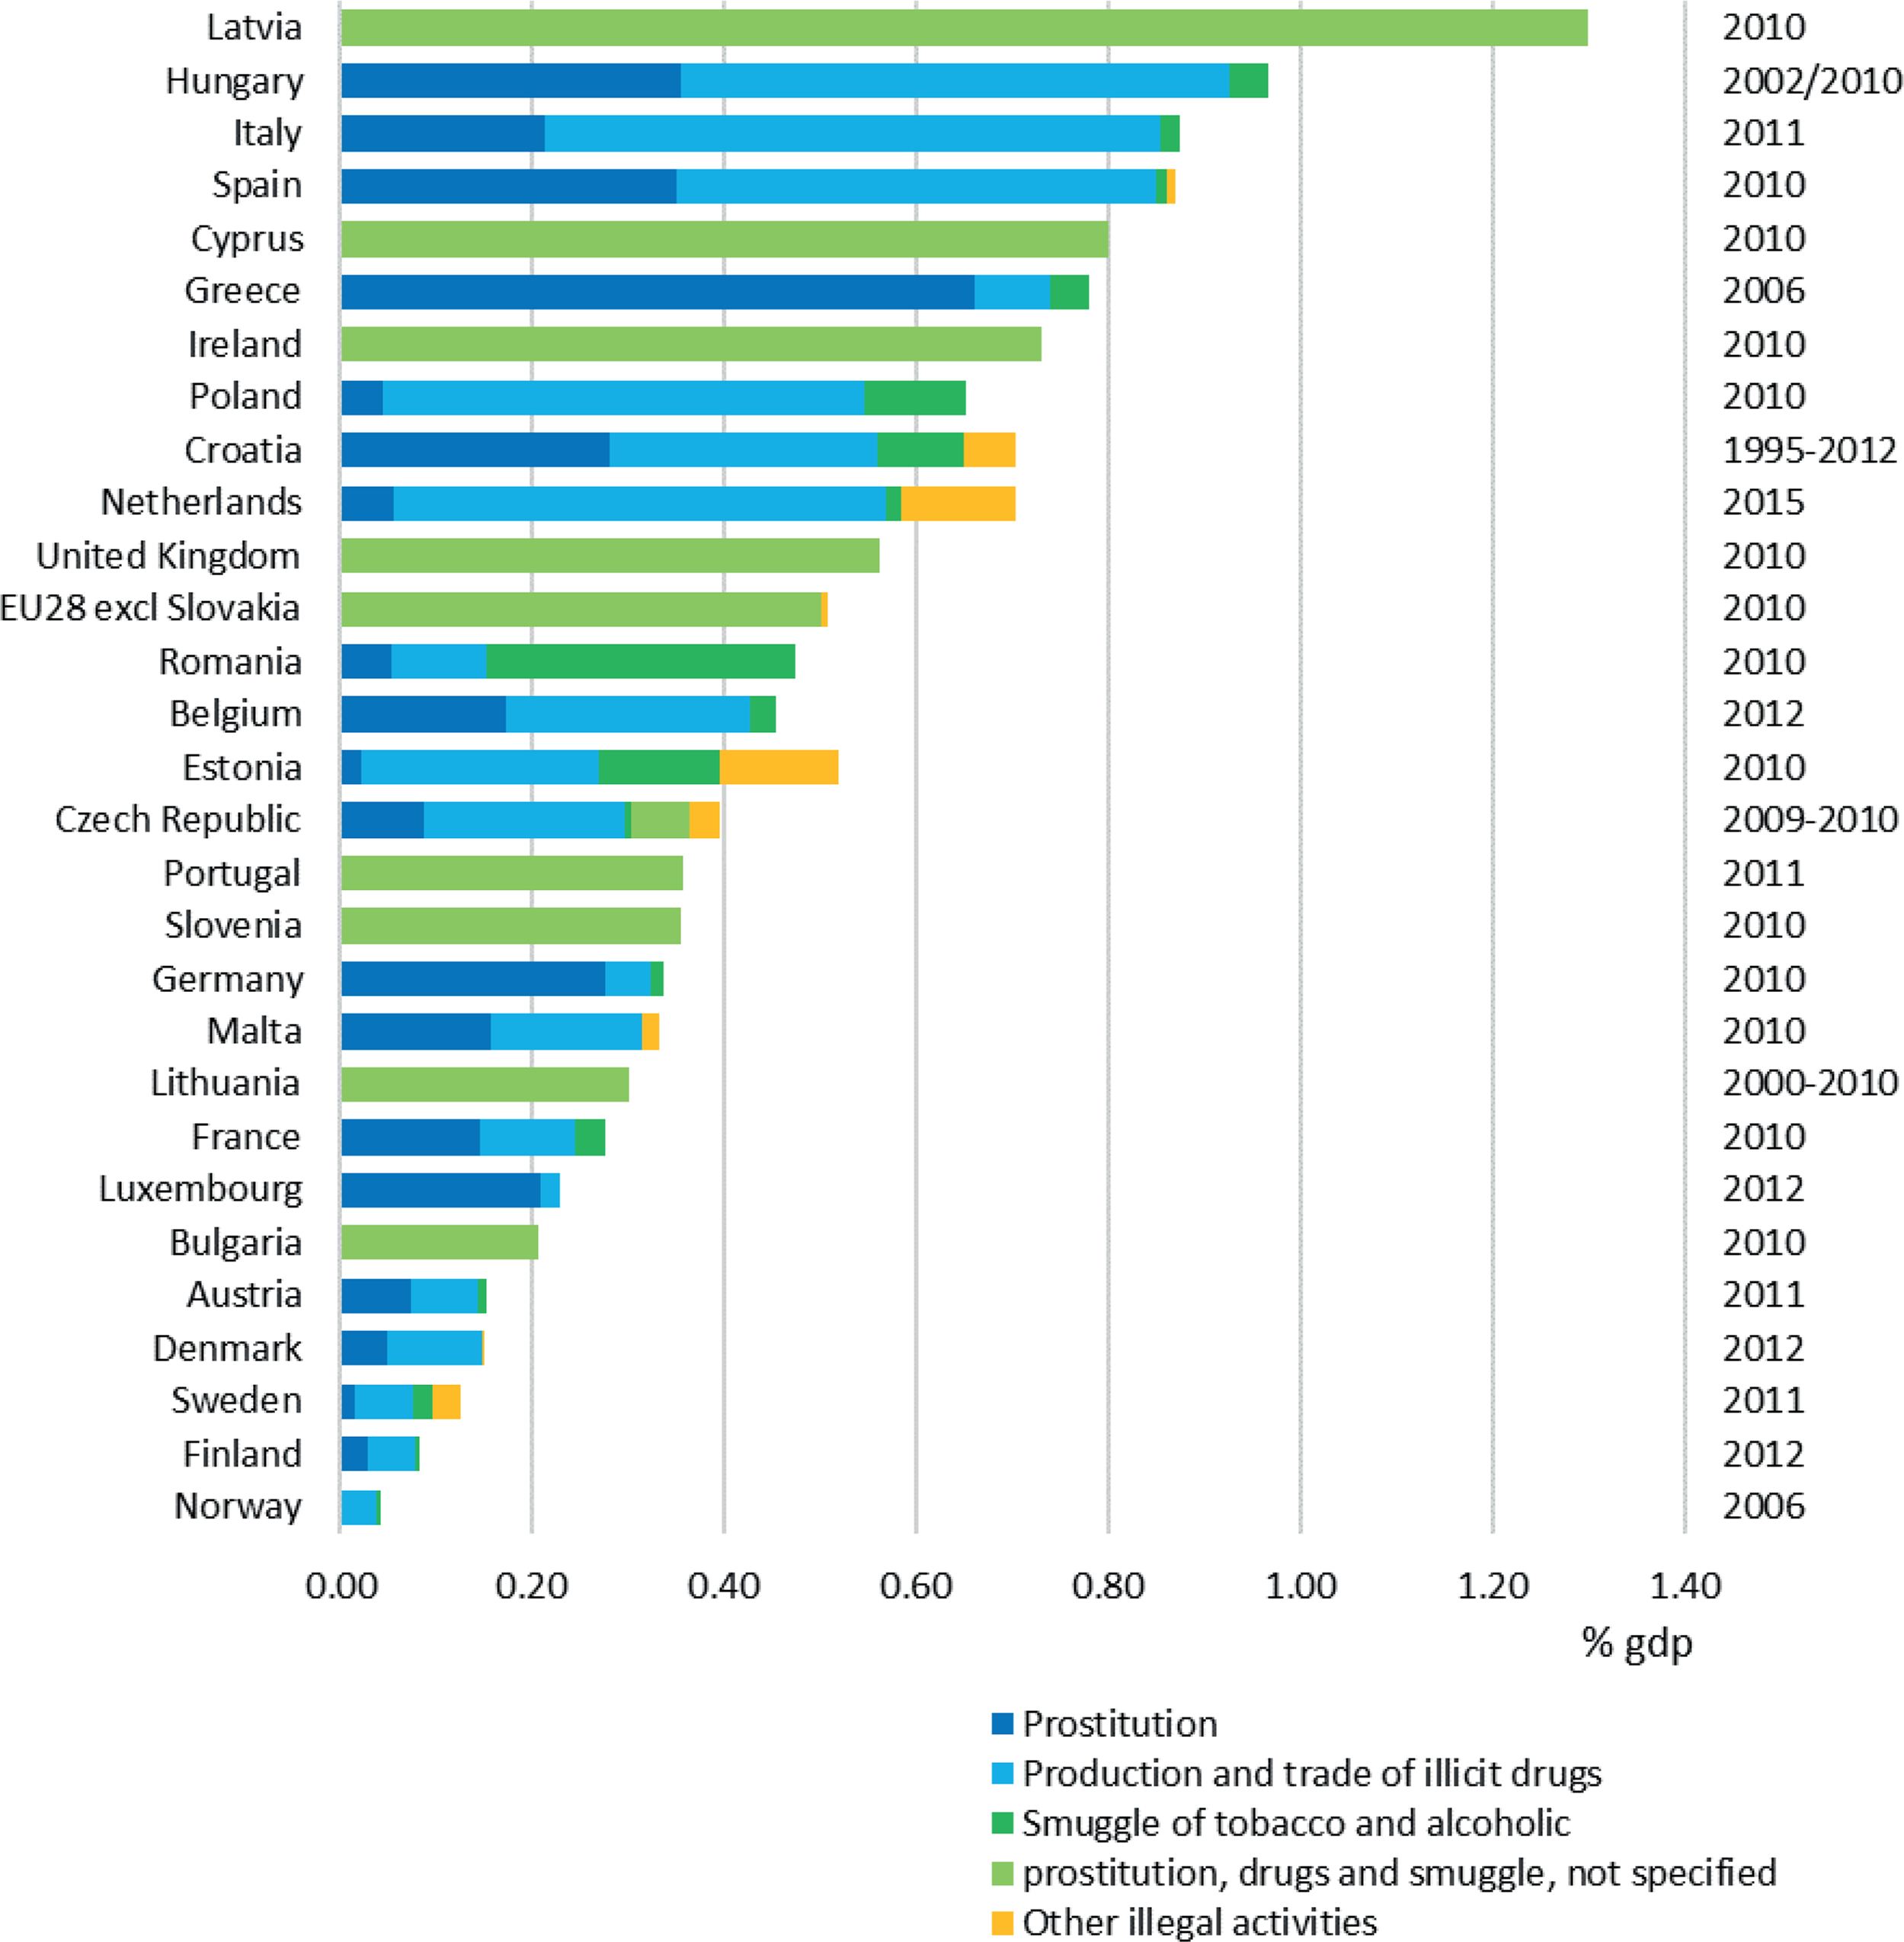
Fig. 3
The value added of N2 illegal activities.3
Tab. 3
Time series of the contribution of illegal activities (N2) to GDP
| Bulgaria | Cyprus | Czech Republic | Ireland | Latvia | Poland | Romania | United Kingdom | |
|---|---|---|---|---|---|---|---|---|
| % of GDP | ||||||||
| 1995 | . | . | . | . | 0.99 | 0.64 | . | . |
| 1996 | . | . | . | . | 1.11 | . | . | . |
| 1997 | . | . | . | . | 0.92 | . | . | 0.92 |
| 1998 | . | . | . | . | 1.59 | . | . | 0.87 |
| 1999 | . | . | . | . | 1.22 | . | . | 0.82 |
| 2000 | . | . | . | . | 0.93 | . | . | 0.77 |
| 2001 | . | . | . | . | 0.88 | . | . | 0.72 |
| 2002 | . | . | . | . | 0.89 | . | . | 0.68 |
| 2003 | . | . | . | . | 0.97 | . | . | 0.61 |
| 2004 | . | . | . | . | 0.91 | . | . | 0.63 |
| 2005 | . | . | 0.59 | . | 0.87 | 0.48 | . | 0.62 |
| 2006 | . | . | 0.49 | . | 0.78 | . | . | 0.71 |
| 2007 | . | . | 0.42 | . | 0.70 | . | 0.46 | 0.68 |
| 2008 | 0.28 | . | 0.37 | . | 0.73 | . | 0.38 | 0.62 |
| 2009 | 0.28 | . | 0.38 | . | 0.99 | . | 0.38 | 0.63 |
| 2010 | 0.21 | 0.8 | . | 0.73 | 1.30 | 0.65 | 0.47 | 0.56 |
| 2011 | 0.22 | 0.5 | . | 0.72 | 1.11 | 0.68 | 0.31 | 0.55 |
| 2012 | 0.23 | 0.4 | . | 0.70 | 1.00 | 0.78 | 0.30 | 0.50 |
| 2013 | 0.27 | 0.4 | . | 0.72 | . | 0.79 | 0.28 | . |
| 2014 | 0.25 | . | . | . | . | . | . | . |
Tab. 4
A tentative estimate of the adjustment for tax evasion, 2015
| Type | Value added | Share tax evasion | Value added hidden because of tax evasion | |
|---|---|---|---|---|
| Million euros | % | Million euros | ||
| House renovations and maintenance | N1 | 742 | 100 | 742 |
| Car repair and maintenance | N1 | 157 | 100 | 157 |
| Food/beverage service activities | N1 | 231 | 100 | 231 |
| Hairdressers and landscaping | N1 | 506 | 50 | 253 |
| Cleaning homes and other buildings | N1 | 1,337 | 50 | 669 |
| Babysitters and childcare | N1 | 316 | 50 | 158 |
| Other | N1 | 362 | 50 | 181 |
| Tips | N3 | 567 | 50 | 283 |
| Renting of dwellings | N3 | 114 | 25 | 29 |
| Cost fraud | N6 | 763 | 100 | 763 |
| VAT gap (intra-community fraud) | N9 | 434 | 100 | 434 |
| Total | 3,900 |
Table A1
The contribution of illegal activities to GDP in Europe