
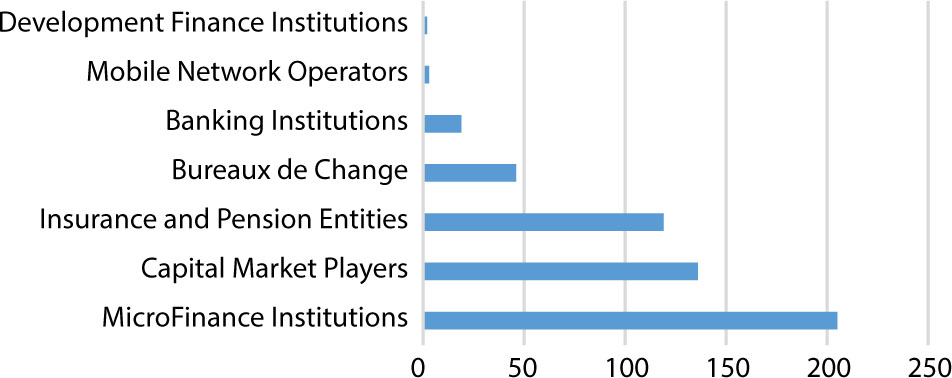
Fig. 1.
Zimbabwe’s Financial Services Outlook (RBZ, 2025)
Source: own elaboration.
Table 1.
Summary statistics for the variables (n = 445)
| Variable name | Observations | Mean | Std. dev. | Variance | Skewness | Kurtosis |
|---|---|---|---|---|---|---|
| Financial inclusion | 445 | 0.950562 | 0.217025 | 0.0471 | –4.15684 | 18.27928 |
| Age of the household head | 441 | 45.38209 | 12.73353 | 162.1429 | 0.300476 | 2.745366 |
| Highest education level | 441 | 4.099773 | 2.443735 | 5.971841 | 0.36687 | 1.945309 |
| Employment status | 441 | 1.578231 | 1.030833 | 1.062616 | 0.337922 | 1.733848 |
| Annual income | 441 | 239.3197 | 414.9766 | 172205.6 | 3.448793 | 17.75139 |
| Financial literacy | 445 | 0.262921 | 0.811292 | 0.658194 | –0.10808 | 2.181049 |
| ICT device ownership | 441 | 1.959184 | 0.198089 | 0.039239 | –4.6414 | 22.54255 |
| Distance to financial institution | 441 | 41.44898 | 35.63282 | 1269.698 | 8.492423 | 129.4015 |
| Membership of savings group | 445 | 0.134832 | 0.341928 | 0.116915 | 2.138843 | 5.572511 |
Table 2.
Distribution of smallholder farmers by type of financial services accessed (Nominal variables, n = 445)
| Financial service | Frequencies (number of respondents) | Percentage (%) |
|---|---|---|
| Mobile money (payment systems) | 150 | 33.6 |
| Savings | 120 | 26.9 |
| Agricultural credit | 90 | 20.1 |
| Agricultural insurance | 60 | 13.4 |
| No services accessed | 25 | 5.6 |
Table 3.
Financial inclusion across demographics and socioeconomic variables (n = 445)
| Category | Financially included (%) | Financially excluded (%) |
|---|---|---|
| Age 18–35 | 45.2 | 54.8 |
| Age 36–60 | 55.8 | 44.2 |
| Age above 60 | 32.1 | 67.9 |
| Gender – Male | 60.4 | 39.6 |
| Gender – Female | 48.7 | 51.3 |
| Primary education level | 35.6 | 64.4 |
| Secondary education level | 50.2 | 49.8 |
| Tertiary education level | 68.4 | 31.6 |
| Employment status (Unemployed) | 28.9 | 71.1 |
| Employment status (Self-employed) | 55.1 | 44.9 |
| Employment status (Employed) | 72.3 | 27.7 |
| Income level (Low) | 30.5 | 69.5 |
| Income level (Medium) | 55.7 | 44.3 |
| Income level (High) | 75.9 | 24.1 |
Table 4.
Financial inclusion by levels (n = 445)
| Financial level | Frequency | Percentage |
|---|---|---|
| Completely excluded | 25 | 5.62 |
| Basic | 150 | 33.71 |
| Partial | 156 | 35.06 |
| Comprehensive | 88 | 19.78 |
| Full | 26 | 5.84 |
Table 5.
Metrics from the goodness of fit test
| Classification confusion matrix and performance metrics | |||
|---|---|---|---|
| Classified | – True – | Total | |
| D | ~D | ||
| + | 307 | 16 | 323 |
| – | 1 | 0 | 1 |
| Total | 308 | 16 | 324 |
| Sensitivity | Pr (+| D) | 99.68% | |
| Specificity | Pr (−|~D) | 0.00% | |
| Positive Predictive Value | Pr (D| +) | 95.05% | |
| Negative Predictive Value | Pr (~D|–) | 0.00% | |
| False + rate for true ~D | Pr (+|~D) | 100.00% | |
| False – rate for true D | Pr (−|D) | 0.32% | |
| False + rate for classified + | Pr (~D|+) | 4.95% | |
| False – rate for classified – | Pr (D|–) | 100.00% | |
| Correctly classified | 94.75% | ||
| Goodness-of-fit test | |
|---|---|
| Statistic | Value |
| Number of Observations | 324 |
| Number of Covariate Patterns | 313 |
| Pearson Chi-square (chi2(299)) | 239.90 |
| Prob > chi2 | 0.9982 |
Table 6.
Results of the logistic regression model on determinants of basic financial inclusion
| Variable | Coefficient | Std. error | z-value | P>|z| | 95% Confidence Interval |
|---|---|---|---|---|---|
| Financial literacy | 0.8794 | 0.198 | 4.44 | < 0.001 | [0.4913, 1.2676] |
| Age category | 0.1882 | 0.1182 | 1.59 | 0.111 | [–0.0436, 0.4199] |
| Financial market proximity (km) | –0.0283 | 0.0071 | –4.02 | < 0.001 | [–0.0422, −0.0145] |
| Highest education level attained | –0.1052 | 0.0596 | –1.76 | 0.078 | [–0.2221, 0.0117] |
| Household size | 0.1078 | 0.0618 | 1.74 | 0.081 | [–0.0133, 0.2290] |
| Farm size (ha) | 0.0058 | 0.0037 | 1.56 | 0.118 | [–0.0015, 0.0130] |
| ICT device ownership | Omitted | – | – | – | – |
| Employment status | 0.0549 | 0.1418 | 0.39 | 0.698 | [–0.2230, 0.3328] |
| Mobile network connectivity | –0.2176 | 0.6193 | –0.35 | 0.725 | [–1.4315, 0.9963] |
| Membership of savings group | –0.9024 | 0.4277 | –2.11 | 0.035 | [–1.7407, −0.0641] |
| Constant (cons) | –0.6431 | 0.8916 | –0.72 | 0.471 | [–2.3905, 1.1044] |